
Hiring nearly stalled in September. The 10-year still touched its highest level since 2002. Europe's bonds cracked, the weakest junk was priced for distress, and Broadcom agreed to lend Anthropic up to $42 billion.
The Fed spent the week backing away from another hike. The bond market did not follow.
October hike odds in futures fell from about 70% early in the week to about 28%. Then Friday's jobs report showed hiring had nearly stalled.
That should have pulled long rates down. It barely did. The 10-year Treasury yield touched 5.34% Thursday, its highest since 2002. It still ended Thursday up 7 basis points on the week. Early Friday, after the jobs data, it sat near 5.2%.
Through Thursday, the S&P 500 was down about 1% for the week. The equal-weight version fell about as much.
So the cost of money now rests less on the Fed and more on lenders. This week showed which borrowers pay the most.
Investing In The Titans of AI
Carnegie didn't invent steel. He used new technology to produce it cheaper and faster than anyone on Earth.
Rockefeller didn't discover oil. He used industrial machinery to refine it more efficiently.
Vanderbilt didn't build the railroad. He understood that whoever controlled the infrastructure controlled the economy.
Their combined fortunes were between $700 billion and $1 trillion.
Best-selling financial author Alexander Green has identified three companies positioned to be the Titans of the AI age.
The Fed Stepped Back, and Hiring Gave It Room
On Tuesday, New York Fed chief John Williams saw "no need for urgency." On Thursday, Vice Chair Philip Jefferson said the Fed may need "more time." Traders now look to December for the next hike.
Prices helped. Core PCE prices rose 3% from a year earlier in August, and traders cut their October bets that day.
Friday gave the bigger push. Employers added just 29,000 jobs in September, the Labor Department said. The jobless rate ticked up to 4.2%. July and August were revised down by 60,000 jobs in all. Hourly pay barely rose.
Not everyone wants to wait. Dallas Fed chief Lorie Logan says rates need to rise another half point or more.
The Signal
Hiring this soft makes an October hike hard to defend. It does not end the cycle, since core prices still run at 3%. Mid-October price data now matters more than any Fed speech.
Long Rates Answered to Something Else
The two-year yield tracks the Fed. It fell 3 basis points on the week through Thursday. The 30-year rose 12.
The 10-year rose 85 basis points last quarter, the most since 1994. Its real yield, after inflation, sat near 2.9% Thursday. That points to investors who want more pay to lend for ten years, not just cover for rising prices.
Oil kept the heat on. Brent topped $102 Thursday after Chinese refiners halted fuel exports. WTI crude fell to about $89 early Friday. Europe was weighing a release of emergency fuel stocks.
Home buyers felt it. The 30-year mortgage rate jumped a quarter point in one week, to 7.28%.
The Signal
A patient Fed can calm short rates. Long rates also answer to oil, debt and global bond supply. If the 10-year holds above 5.2% after weak jobs data, the bond market is tightening for the Fed.
Hidden in Tesla's Filing: A $12 Billion "Super Startup"
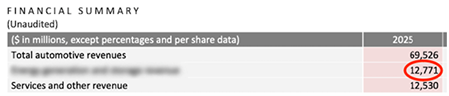
Pull up Tesla's most recent SEC filing. Page 5.
And you'll see a single line showing $12 billion in revenue from a brand-new "super startup" Elon Musk has been quietly incubating inside Tesla.
This new "super startup" has nothing to do with cars or robots or space or AI…
But it sits at the center of what Blackstone calls "a $23 trillion investment opportunity."
And on Oct 21st, Elon is expected to pull back the curtain and reveal exactly what he's building.
But Adam O'Dell already knows… and he reveals it all in this urgent video.
Europe Became the Weak Link
On Thursday, bond buyers picked sides. Treasurys and German bonds rallied. French, Italian and Greek debt sold off.
France's 10-year premium over Germany hit about 1.33 points, its widest since May 2012. Britain's 30-year yield topped 6% for the first time since 1998. The euro fell to a 17-month low.
Forced selling sped it up. Hedge funds had to unwind bullish bets on French debt, traders said. Part of the Treasury rally looked like money seeking safety.
Friday brought no relief. Euro-area inflation jumped to 3.8%, mostly on energy.
The Signal
Hotter prices give the ECB less room to step in. The French spread is the tell. A drift back near 1.2 points would point to a global selloff. A spread that stays above 1.3 would mean France now pays a premium of its own.
Credit Charged the Weakest Borrowers Most
CCC bonds, the lowest tier of junk, hit 1,007 basis points over Treasurys on Wednesday. That level usually signals a high chance of default. It was 860 at the start of September. The last time they topped 1,000 was March 2023. B-rated bonds held fairly steady.
Big deals paid up too. Paramount Skydance (PSKY) is buying Warner Bros. Discovery (WBD). It sold about $52 billion of bonds to pay for it. By Thursday, yields on some topped 10%, up from as high as 9% at sale.
Even a fully leased data center paid a steep rate. A venture tied to Blue Owl (OWL) sold notes for a Virginia site at a coupon near 8.9%. That is almost 4 points over five-year Treasurys.
The Signal
Lenders are still lending. They now sort by debt load and cushion, and they charge for both. If B-rated spreads start to widen, the strain has climbed past the bottom tier.
Porter Stansberry's Critical New Warning:
Trump Is Replacing The U.S. Dollar
"The last time America reset its money, it created 1,300 millionaires every day. This could be bigger."
AI's Suppliers Became Its Lenders
Broadcom (AVGO) agreed to lend Anthropic up to $42 billion, its draft IPO filing shows. The notes can turn into stock. They could cover about a third of a $125 billion lease for chips Broadcom helps design. The filing flags "potential conflicts of interest."
Nvidia (NVDA) went first. It could back up to $500 billion of its buyers' data-center loans, though only in part.
Private money kept flowing too. OpenAI is in early talks to raise at least $30 billion in place of an IPO. It seeks a value near $1.4 trillion before the new cash. No terms are final.
The demand behind it is real. Micron (MU) expects sales of about $61.5 billion this quarter, well above forecasts. Its stock rose about 3% Thursday, less than options had priced.
The Signal
Vendor loans speed the build. They also tie a supplier's sales to its buyer's power to pay. Watch whether Anthropic's public filing names a lending partner or sets terms for turning notes into stock.
Locked Money Kept Coming. Exits Narrowed.
On Tuesday, profitable Oura pulled its $2.1 billion IPO hours before pricing. Nearly three-quarters of the shares were coming from current holders. Accelevation (ACCV) priced its IPO below its range and opened lower. Anthropic now aims to list before Thanksgiving, people familiar said.
Locked-up money kept arriving. Five closed-end funds reported about $9.5 billion of new pledges. Audax closed at a $5.4 billion cap, well past its goal.
Funds that promise easy exits had a rough week. Australia's Metrics Credit Partners froze withdrawals at several funds. The SEC proposed wider retail access and looser buyback rules for funds that often cap withdrawals.
The Signal
The split runs by fund design, not asset class. Closed-end funds can wait out a slow deal market. Funds with exit windows must pay out first. S&P has set Oct. 28 for Metrics' audited accounts.
Middle East Conflict Lights Fuse on US Debt Bomb
America was already drowning in $38 trillion of debt, but the recent conflict in the Middle East just accelerated the timeline.
As oil spikes, a 100-year-old stock market signal that accurately predicted the 2008 and 2020 crashes is flashing a massive "Sell" on dozens of popular U.S. equities.
If you hold the wrong stocks when this debt crisis hits, it could wipe out years of gains.
Click here to see the 10 popular stocks to dump immediately
11780 US Highway 1, Palm Beach Gardens, FL 33408-3080 Would you like to edit your e-mail notification preferences or unsubscribe from our mailing list? Copyright © 2026 Weiss Ratings. All rights reserved.
Six takeaways. One shift ran under all of them.
The Fed stepped back, and a weak jobs report backed it. Long rates did not take the hint. Europe's shakiest bonds cracked. The lowest-rated borrowers were priced for distress, and a fully leased data center still paid nearly 9%.
Money did not stop. Suppliers lent to their buyers. A private round may stand in for an IPO. Closed-end funds filled up while Metrics froze withdrawals.
The week settled one thing. The Fed no longer sets the cost of money alone. Lenders do, one borrower at a time. It left open whether softer hiring finally pulls long rates down, or the bond market keeps pressing.
3 Stocks at a Major Turning Point
Something unusual is happening beneath the surface of three widely followed stocks.
In each case, the fundamentals are saying one thing... while institutional activity, management signals or the options market are saying something else.
That kind of disagreement can matter.
Because when the evidence stops lining up, the next move in the story often comes down to a handful of signals most investors never think to watch.
Our new FREE Market Tell Special Report breaks down three of these situations, and shows you exactly what we’re watching next.