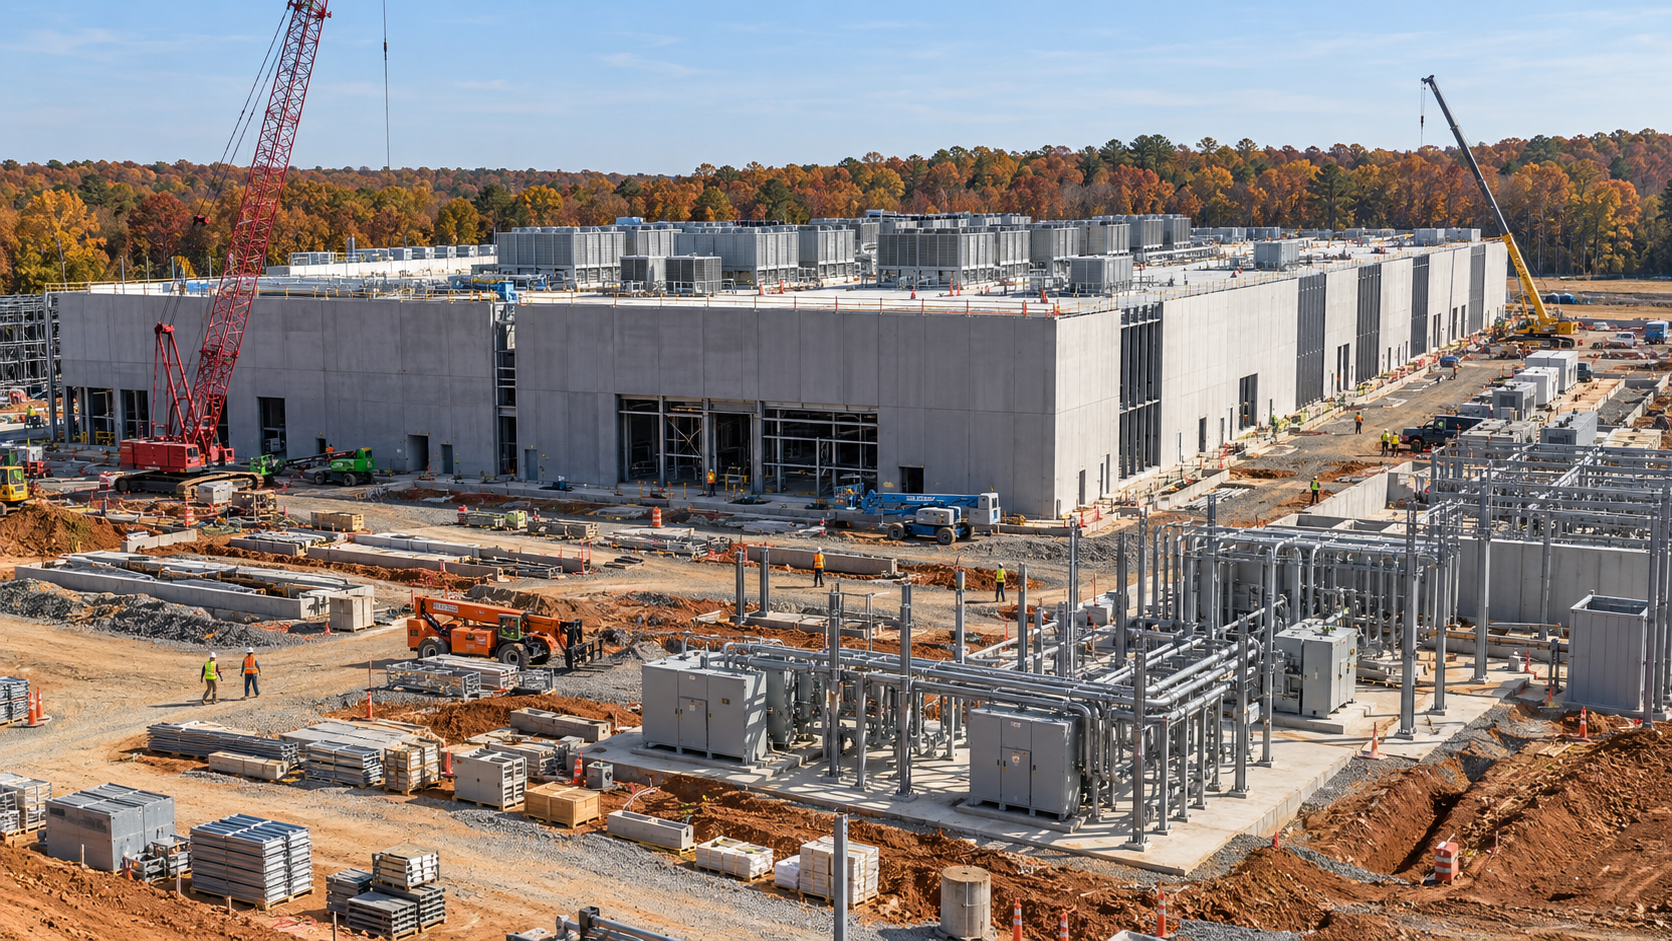
A Blue Owl joint venture sold $1.12 billion of five-year secured notes to fund a 76-megawatt facility, at a coupon nearly 4 points above Treasuries.
The cost of financing the artificial-intelligence building boom now has a fresh, public data point.
DDC 01 Propco, owned by a joint venture of PowerHouse Data Centers, Cedarwood Investment Group and Blue Owl Capital affiliates, priced $1.12 billion of 8.875% senior secured notes due 2031. The notes were sold under Rule 144A and Regulation S. The money will help build a facility in Virginia's Chesterfield County with 76 megawatts of critical IT load, a project "fully leased under a long-term triple-net lease." The tenant has not been disclosed.
The cost per megawatt
The financing works out to about $14.7 million of debt for each megawatt of capacity. Because the notes fund only part of the project, total development cost per megawatt is higher still. Those figures illustrate how capital-intensive the race for AI computing capacity has become.
The spread over Treasuries
With five-year Treasuries yielding 5.09% on Wednesday, the notes' 8.875% coupon is roughly 380 basis points higher. This is a coupon comparison, not a precise yield spread: that calculation would require the notes' issue price and yield at pricing.
That is a substantial difference for a facility described as fully leased under a long-term triple-net arrangement. Possible contributors include concentration in one undisclosed tenant, construction risk and uncertainty over the economics of AI infrastructure. Without the issue yield and fuller credit details, the pricing cannot isolate the contribution of each risk.
The backdrop
The pricing comes a week after Oracle invoked force majeure on Project Jupiter, a separate Blue Owl data-center development. There is no disclosed connection between the two projects, but the episode has put counterparty and execution risk in data-center development squarely in front of investors.
The broader rate environment adds to the cost. The financing priced as long-term Treasury yields reached their highest levels since 2002, raising the base on which every risk premium sits.
Why it matters
Private-credit and infrastructure investors have poured money into data centers on the assumption that long leases with large technology companies make the debt safe. An 8.875% coupon suggests the market prices that safety less generously than the lease structure alone implies. If more projects price at similar levels, the cost of capital could slow the pace of new development.
What to watch
Disclosure of the tenant would clarify how much of the spread reflects credit risk versus project risk. Further data-center financings in coming weeks will show whether 8.875% is an outlier or the new benchmark for AI infrastructure debt.