

Last week, Meta's spending ran past its cash. Stocks, credit and private rounds all charged more to fund AI. Brent climbed to near $116, and bonds rallied anyway.
This week asks whether AI's other giants can still pay their own way. Microsoft (MSFT) and Alphabet (GOOGL) report Wednesday evening. Amazon (AMZN) reports Thursday.
A few hours before Microsoft and Alphabet, the Fed announces its decision. Thursday brings third-quarter GDP and the Fed's preferred inflation gauge.
And Brazil's runoff count should be in before Monday's open.
Five tests, then the calendar.
Before the AI Wealth Gap Widens, See This List
Blue-chip stability meets AI growth in 7 AI Stocks to Invest in Today
Inside: a top-10 dividend payer rolling out AI-powered logistics across 200 countries… a $300B titan embedding AI across its full product stack… and a semiconductor leader still trading 15% below its 52-week high.
All proven operators, all using AI to widen their lead.
See the list for free today – after that, you’ll have to pay.
1. Can AI's giants still pay their own way?
Microsoft reports after Wednesday's close. Alphabet's call follows at 4:30 p.m. ET. Amazon reports Thursday, with its call at 5 p.m. ET.
Meta set the bar last week. Its third-quarter capital spending exceeded the cash its business generated, and it built a non-voting stock to raise more. The question for the other three is the same. Does operating cash still cover the build?
Watch three lines: capital spending, operating cash flow and any first number for 2027. Listen for cloud backlog too. A draft Anthropic prospectus seen by The Wall Street Journal showed $111 billion of cloud agreements with Google and $110 billion with Amazon Web Services.
Strong backlogs and cash that covers capex would make Meta look like the outlier. Spending above cash, or new talk of debt and partners, would make Meta look like the first of several.
2. Does the Fed agree with the bond market?
The Fed meets Tuesday and Wednesday. The decision lands Wednesday at 2 p.m. ET, and Chair Kevin Warsh speaks at 2:30. The Fed raised rates in September to a 3.75% to 4% range.
Traders expect a hold. Kalshi priced it near 94% on Friday morning, with a hike near 6%. They still lean toward a December hike.
Last week the bond market bet that $116 oil hurts growth more than it lifts prices. Warsh gets to say whether the Fed sees it the same way. Thursday's data test it again. Third-quarter GDP and September's PCE inflation both land at 8:30 a.m.
A statement that stresses growth risk would back last week's bond rally. One that stresses oil and consumers' 4.7% inflation expectations would pull December back to the center, and could push the 10-year back above 5%.
Porter Stansberry's Critical New Warning:
Trump Is Replacing The U.S. Dollar
"The last time America reset its money, it created 1,300 millionaires every day. This could be bigger."
3. The bond market votes three more times
The Treasury sells 2-year notes Monday, 5-year notes Tuesday and 7-year notes Thursday. Those sales bracket the Fed decision.
Last week's sales sent mixed signals. The 20-year bond found buyers, but only at 5.469%, above September's yield. The five-year TIPS sale drew softer demand than last time.
Strong demand at the shorter maturities would back the growth read. Weak demand around a firm-sounding Fed would undo it.
Watch Meta's credit alongside. Last week its default swaps rose while Treasury yields fell. If that gap keeps widening, cheaper government money isn't reaching AI's borrowers. Microsoft, Alphabet and Amazon will be judged partly on whether they need that money at all.
4. Who pays for $116 oil
Brent ended the week near $116. U.N. Ambassador Mike Waltz told the Financial Times the war with Iran could last another year. The companies on both sides of that price report this week.
Ford (F) reports Wednesday, with its call at 5 p.m. ET. It is the first chance to hear whether GM's $2 billion commodity warning is an industry problem. Coca-Cola (KO) reports Tuesday before the open. Visa (V) reports Tuesday after the close. Exxon Mobil and Chevron are scheduled for Friday.
Ford describing the same squeeze would make GM's caution a sector story. Visa reporting steady card spending would ease the shopper worry Deckers raised. Oil majors holding back spending at these prices would say they don't trust $116 to last.
FREE Gold Ticker to Buy ASAP: (NYSE:___)
Jim Rickards – the world’s #1 gold expert – has just revealed one of his favorite gold plays… 100% FREE
As Jim sees it, we’re witnessing the biggest gold boom of the last 100 years – and those who keep their money on the sidelines are missing their chance at a fortune thanks to gold’s epic run.
But smart investors who get in now, could make 10X their money in the coming months.
5. Two verdicts on government risk
Brazil's polls close at 4 p.m. ET Sunday. The polls call it a tie. Datafolha's final survey has Flávio Bolsonaro and Lula at 50% of valid votes each. The betting markets don't. Polymarket priced Bolsonaro near 77 cents Friday morning, and Kalshi near 76.
A contract price is a chance of winning, not a vote share. A Lula win would be the bigger surprise for anyone who trusted those odds over the polls. Watch the real and Brazilian stocks Monday.
France has its own verdict. Moody's reviewed France's Aa3 rating after Friday's U.S. close. [UPDATE BEFORE SEND: insert Moody's decision in one sentence.] The French 10-year touched 5.06% last week, its highest since 2002, while Treasuries and Bunds rallied.
Read more: French borrowing costs rose while global bonds rallied
6. The week on one page
All times ET.
- Sunday: Brazil presidential runoff. Polls close 4 p.m.
- Monday: 2-year note auction. Verizon and Nucor report.
- Tuesday: Fed meeting begins. Coca-Cola before the open. Consumer confidence, 10 a.m. 5-year note auction. Visa after the close. UPS, Boeing and PayPal also report.
- Wednesday: Bank of Canada decision. Fed decision, 2 p.m., and Warsh press conference, 2:30 p.m. Microsoft and Ford after the close. Alphabet call, 4:30 p.m. Strategy (MSTR) holds a special shareholder meeting.
- Thursday: Q3 GDP and September PCE inflation, 8:30 a.m. ECB decision. 7-year note auction. Bank of Japan meeting begins. Mastercard, Caterpillar, Eli Lilly, Blue Owl, Strategy and Coinbase report. Amazon after the close, call at 5 p.m.
- Friday: Bank of Japan decision. Exxon Mobil and Chevron report. Bitcoin options expire.
Hidden in Tesla's Filing: A $12 Billion "Super Startup"
Pull up Tesla's most recent SEC filing. Page 5.
And you'll see a single line showing $12 billion in revenue from a brand-new "super startup" Elon Musk has been quietly incubating inside Tesla.
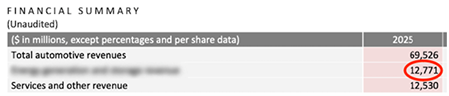
This new "super startup" has nothing to do with cars or robots or space or AI…
But it sits at the center of what Blackstone calls "a $23 trillion investment opportunity."
And on Oct 21st, Elon is expected to pull back the curtain and reveal exactly what he's building.
But Adam O'Dell already knows… and he reveals it all in this urgent video.
THE MARKET SIPS TAKEAWAY
Last week showed what happens when AI's biggest buyer outspends its cash. This week shows whether Meta is alone.
If Microsoft, Alphabet and Amazon cover their builds from cash and the Fed sounds worried about growth, last week looks like a Meta problem. If they lean on outside money and the Fed leans on oil, the funding question moves to the whole AI trade.
UNTIL THEN, SIP SLOWLY!
The Market Sips Desk
REPLY PROMPT:What would Microsoft have to say Wednesday to convince you AI's giants can still pay their own way? Hit reply.
Rates Just Reset. Who Feels It First?
On January 2, the 10-year yielded 4.19%. By September 30, 5.29% — most of it in one quarter.
Some companies earn from higher rates. Some pay. Each runs on a different clock.
We traced three: IBKR, WRB and FIS. One has already reported. The other two report next, and the report tells you the exact line to check.
Free report, texted to your phone.