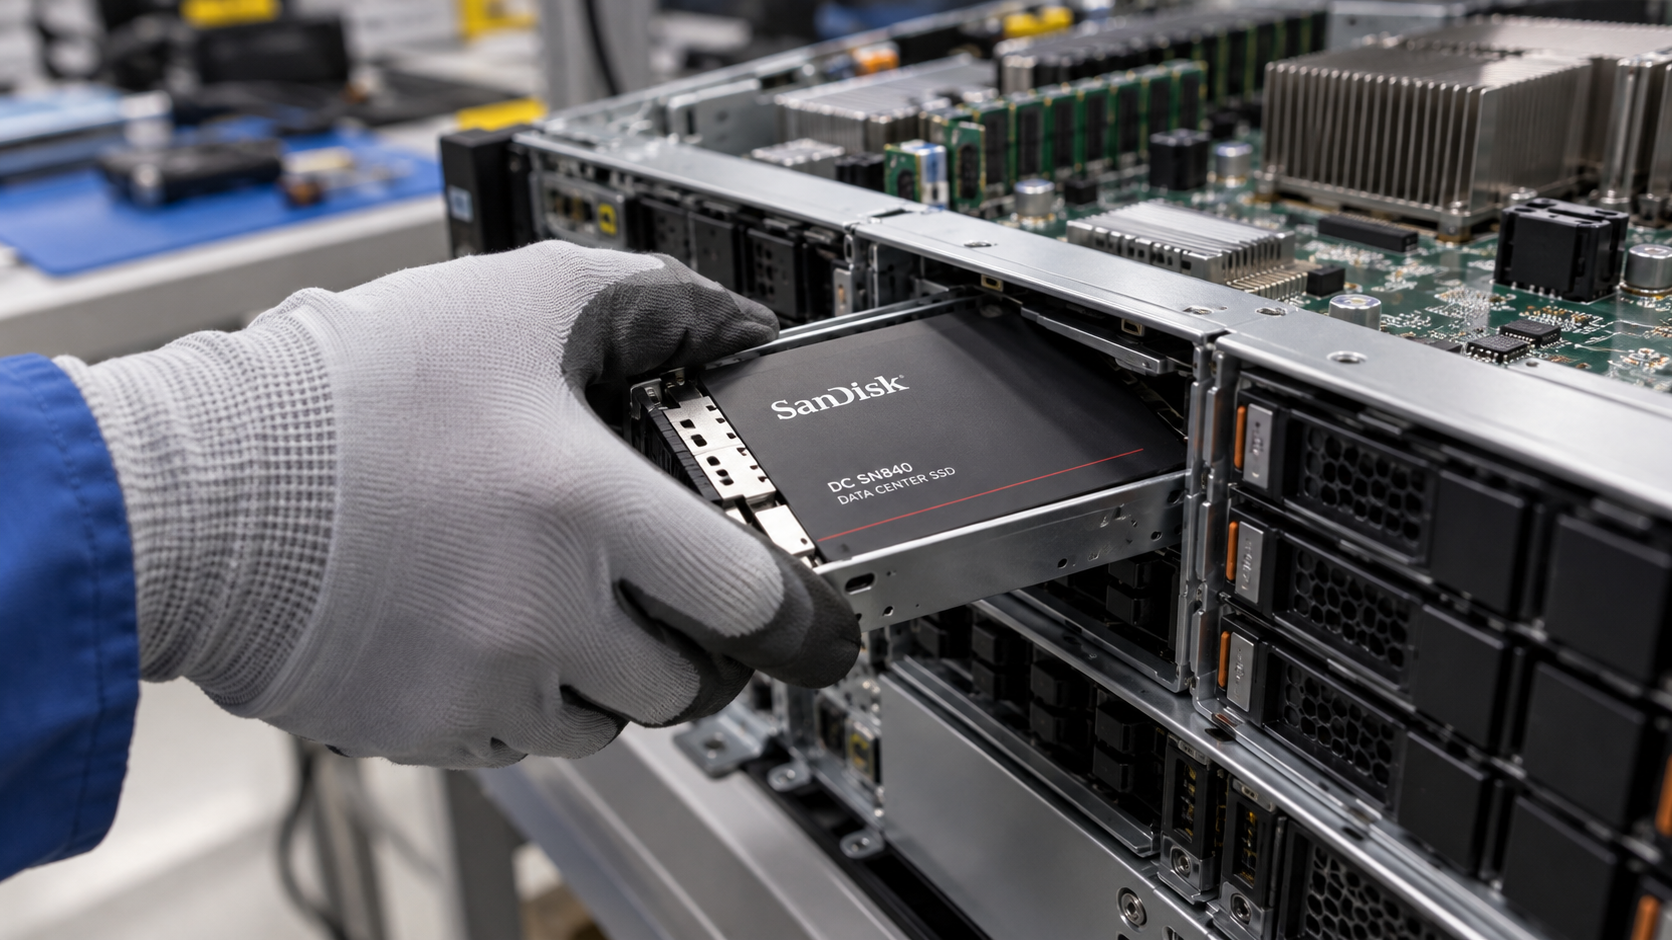
The flash-memory maker reported fiscal first-quarter revenue of $11.03 billion, up 378% from a year earlier, a gross margin of 85% and guidance above estimates. The shares slipped about 4% in extended trading, after falling 5.3% during the day as chip stocks sold off.
By almost any measure, Sandisk's quarter was extraordinary. Its shares still went down.
For the fiscal first quarter, which ended Oct. 2, revenue was $11.03 billion, up 23% from the previous quarter and 378% from a year earlier. The gross margin was 85.0% on a GAAP basis and 85.1% adjusted. Adjusted earnings were $49.51 a share, above the $47.15 analysts expected, and GAAP earnings $52.60. Revenue beat the roughly $10.7 billion forecast. Datacenter revenue rose 61% from the prior quarter to $4.80 billion. Adjusted free cash flow was $5.7 billion.
The outlook and the split
Sandisk expects fiscal second-quarter revenue of $12.2 billion to $12.6 billion, against an estimate of $12.23 billion, and adjusted earnings of $55 to $57 a share.
It also announced an 8-for-1 stock split, effective Nov. 19, with shares trading on a split-adjusted basis from Nov. 20. All per-share figures above are before the split.
The reaction
Sandisk closed at $1,330.05 on Thursday, down 5.32%, before the results, as chip stocks fell. In extended trading it slipped another 4.1% to about $1,275.50.
Why a beat was not enough
The guidance is above expectations, but not by much. The $12.4 billion midpoint is about 1.4% above the estimate, by our arithmetic. For a company whose revenue has nearly quintupled in a year, investors were looking for a bigger step up, and they were doing so on a night when Intel's forecast and Amazon's results were pulling the whole semiconductor group lower.
A gross margin of 85% also raises its own question. That level reflects memory prices well above what it costs to make the chips. The market's debate is how long such pricing lasts.
Peak or plateau?
The plateau view: datacenter revenue grew 61% in a single quarter, guidance points higher again, and the split could broaden the shareholder base.
The peak view: margins at 85% leave little room to improve, the guidance beat is narrow, and in a cyclical business like memory, pricing can turn quickly once supply catches up.
What to watch
Friday's regular-session trading, datacenter revenue against this quarter's $4.80 billion, the second-quarter gross margin, and the split on Nov. 19.