

Nasdaq fell 0.56%, WTI gained 1.76%, and September hike odds rose to 87% as Anthropic held 96.2% AI-model odds.
Monday turned the morning warning into a closing tape.
The Nasdaq fell 0.56%. The S&P lost 0.48%. The Dow slipped 0.29%. The VIX rose 7.95% to 17.10.
The 10-year yield rose to 4.99%. Oil gained 1.76% to $101.81. Gold fell 1.6%. The dollar ended the day higher.
The same three pressures held all day. AI stopped trading as only a growth story. Oil stayed above $100. The Fed meeting moved further toward a hike.
The September book now prices a 25 basis point increase at 87%. No change is 13%. The 10-year touching 5.0% before 2027 sits at 93%.
Friday’s stock bounce did not survive the weekend. Monday did not need a crash to change the week. It only needed the growth trade to pay a higher price.
There's a Strategy Behind the Iran War.
I know because I've seen the evidence firsthand.
On March 2nd — three days after the first missiles hit — I sat across from two U.S. Congressmen in back-to-back private meetings.
Those meetings pointed me toward something I spent weeks verifying.
The real purpose behind the strikes. The real objective. And the single company at the dead center of all of it.
This isn't random. It's a calculated Two-Front Economic War.
And there's one company positioned right at the heart of it.
See the strategy behind the Iran war — and the company at the center of it
The sooner you understand what's really happening — the better positioned you'll be before
— Dylan Jovine, Founder, Behind the Markets
The AI trade sold off because the brake became political.
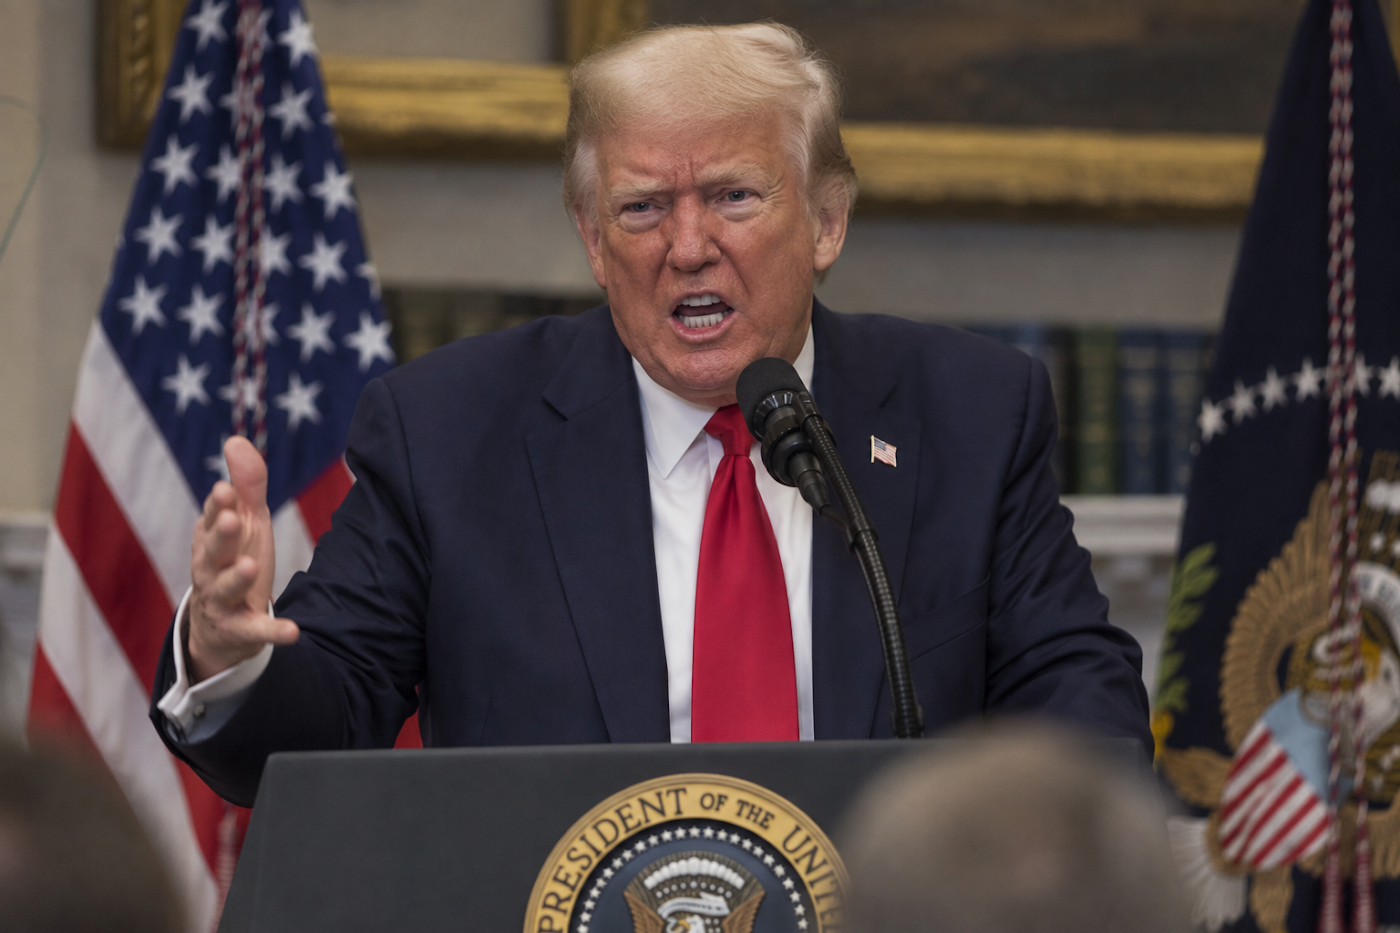
Dario Amodei called for slowing frontier AI development. Sam Altman and Elon Musk backed the broader pacing argument. President Trump rejected it and said slowing down would help China.
That changed the risk.
The question is no longer only whether AI demand is strong. It is whether the pace of model progress can stay fast enough to justify the buildout, while Washington argues over guardrails.
Nvidia (NVDA) fell 3.4%. Broadcom (AVGO) lost 4.8% and Advanced Micro Devices (AMD) dropped 4.4%. Intel (INTC) lost over 5.5%. Marvell Technology (MRVL) slid more than 7.3%.
Cybersecurity names moved differently. CrowdStrike (CRWD) gained as investors treated AI safety as a risk-control spend, not just a chip cycle.
Prediction markets narrowed the same story. Anthropic sits at 96.2% to have the best AI model at the end of September. Google sits at 1.8%. OpenAI sits at 1.3%. Meta Platforms (META) is below 1%.
The Brake That Reprices Time
A safety fight does not end AI demand. It changes the payback clock.
Oil kept the macro brake in place.
WTI settled near $102. Brent closed over $106 after almost touching $110 earlier in the day. The reason was not only Hormuz.
Saudi Arabia’s East-West pipeline remains shut after drone damage. The line can move up to 7 million barrels a day from Gulf oil fields to Red Sea ports. It was the backup route when the Strait of Hormuz was unsafe.
Now the backup route has its own risk.
Kpler warned the market could lose 120 million barrels if the line stays closed for a month. Iran-Gulf talks in Oman were postponed. Houthi advances near Bab el-Mandeb added another threat to Red Sea flows.
The pump book moved with crude. Kalshi traders now see a 71% chance that the national gasoline average crosses $4.60 before year-end. This year’s high was $4.56 on May 21.
The Bypass That Became the Risk
Oil risk moved from the Strait to the route around it.
Navellier Warns: This Could Leapfrog Elon's SpaceX IPO
Elon Musk could take SpaceX public in 2026, at an estimated $1.75 trillion valuation. The IPO would include Elon's AI model, Grok. But according to Louis Navellier, a radical new AI model will launch this year… over 1,000 times more powerful than Elon's. And the company behind it could outperform SpaceX in the process.
Click here for full details (including Louis' new pick — free).
This ad is sent on behalf of InvestorPlace Media at 1125 N. Charles Street, Baltimore, Maryland 21201. If you're not interested in this opportunity, please click here.
The rate market priced both brakes at once.
The 10-year touched 5% during the session before closing near 4.99%. That is the line the morning letter said was no longer a tail.
Prediction markets kept it there. A 5.0% touch before 2027 sits at 93%. A 5.1% touch is 65%. A 5.2% touch is 33%. Each rung prices a different amount of stress, and the first one is now effectively spoken for.
The Fed book moved with it. September hike odds rose to 87%. October no-change is 62%, with a hike at 37%. December prices a 25 basis point hike at 57% and no change at 40%. A hike at any point in 2026 sits at 93%.
Crypto policy moved the other way. The Clarity Act signed into law in 2026 fell to 26%, down from near 30% after the revised Senate text. Supporters still need 60 votes to advance the bill, and the Senate holds its procedural vote Tuesday.
Growth is not gone. Polymarket still prices 2026 GDP growth between 2.0% and 2.5% at 58% odds.
The Ladder With One Rung Filled
A 93% reading on a 5% touch is not a forecast, it is a rung that has already been paid for. The rungs above it price how much further the stress runs, and they thin out fast. So the long end has stopped arguing about whether yields get there and started arguing about what happens next. Watch where the ladder breaks, not where it starts.
Three clocks ran Monday and none of them are set by the Fed.
AI sets the earnings clock. A safety fight does not cancel demand, it extends the payback period on capital already committed. Oil sets the inflation clock, and a shut pipeline moves on repair schedules rather than headlines. The Fed sets neither. It only prices what the other two produce.
The prediction-market books show the same layering. Anthropic holds 96.2% for the best model at the end of September and 70% by January. September prices an 87% hike, October leans back to no change at 62%, December swings toward a hike again at 57%.
The near date is settled in both books. The far date is not. That is the same shape in two unrelated markets, which is usually a sign the uncertainty is about time rather than about direction.
The Clock the Fed Does Not Set
A rate decision is the only one of Monday's three clocks with a date on it, which is why it gets the most attention and explains the least. AI capex and a damaged pipeline both run on schedules nobody votes on, and both feed the number the Fed eventually has to answer. Pricing the meeting is easier than pricing the inputs, so that is where the liquidity goes. The decision is dated. The things that decide it are not.
FREE Gold Ticker to Buy ASAP: (NYSE:___)
Jim Rickards – the world’s #1 gold expert – has just revealed one of his favorite gold plays… 100% FREE
As Jim sees it, we’re witnessing the biggest gold boom of the last 100 years – and those who keep their money on the sidelines are missing their chance at a fortune thanks to gold’s epic run.
But smart investors who get in now, could make 10X their money in the coming months.
Monday answered the morning with confirmation, not resolution.
AI slowed the Nasdaq. Oil held above $101. The 10-year touched 5%. The Fed book moved to 87% for a September hike.
What is priced: Anthropic’s month-end model lead, a 5% 10-year touch, a September hike, and gasoline risking fresh 2026 highs.
What is not priced: AI capex slowing before guidance changes, the Saudi pipeline staying shut for weeks, gas over $4.60 feeding expectations, or prediction-market volume meeting new state and federal limits.
The growth trade still exists.
It just costs more to carry.
Capital moves early. Coverage catches up. The gap between the two is worth watching.
THE MARKET WON’T WAIT FOR YOUR INBOX
Get the Alerts That Could Move Your Money
Breaking market news, actionable trade ideas, analyst signals, and major catalysts—sent straight to your phone when they matter.
Join FinancialMarkets.comFREE market alert list today.
SEND ME THE NEXT ALERT → (free)