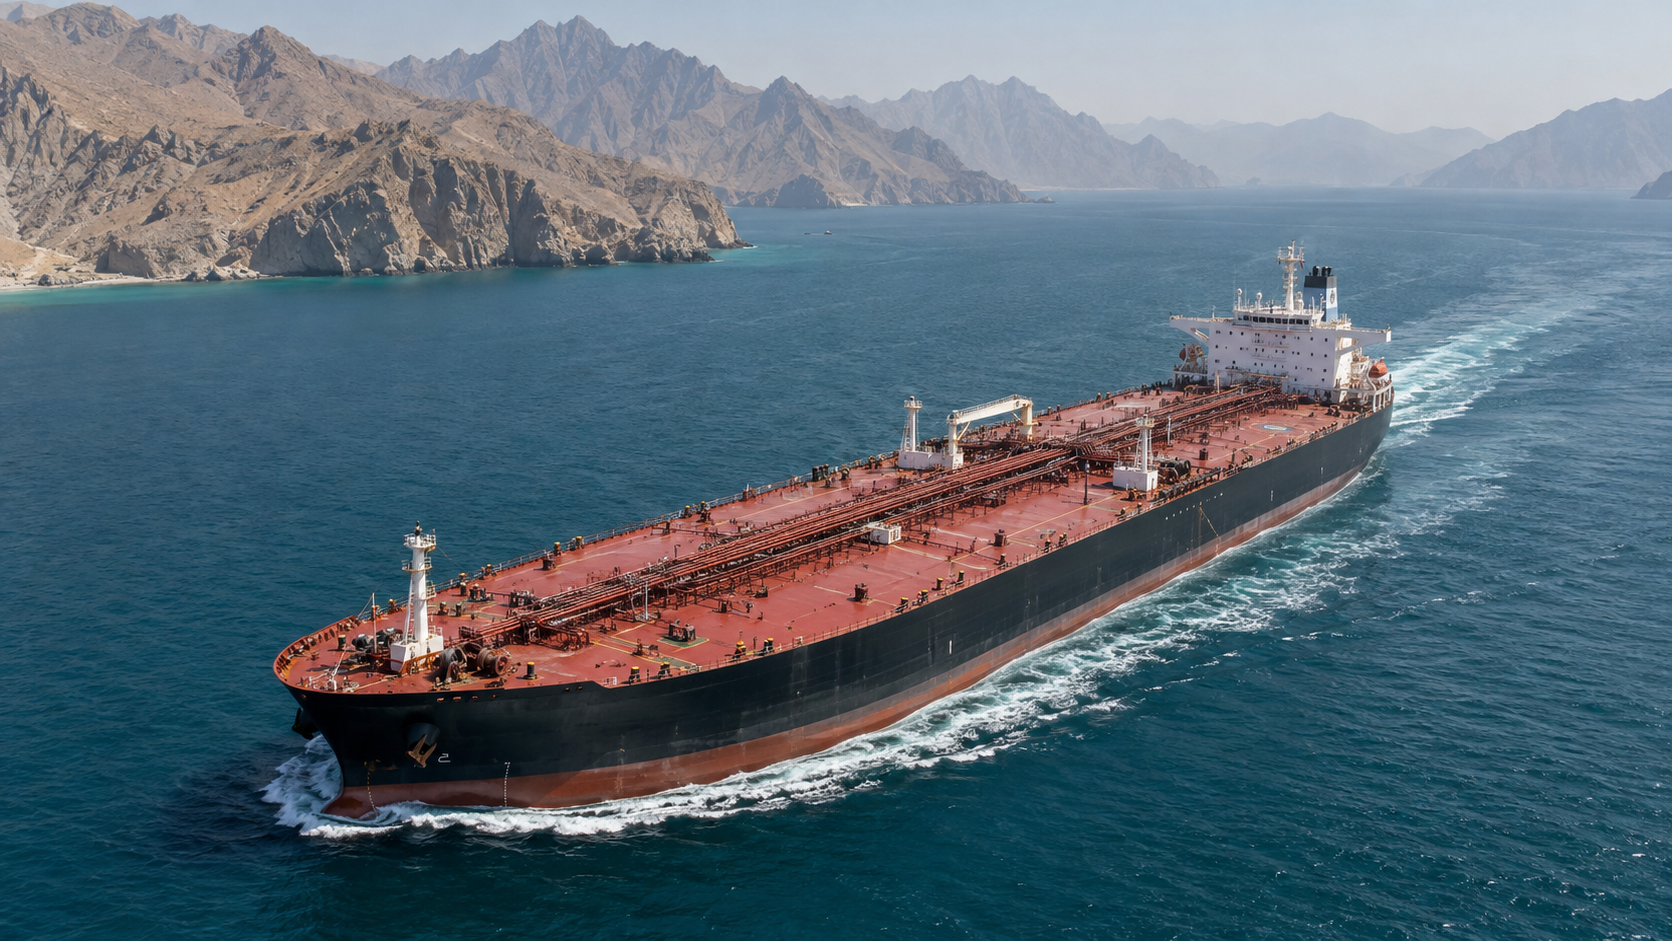
Kpler data show flows through the Strait fell to about 11.6 million barrels a day last week, roughly a third below the firm's baseline, and the IEA committed less diesel than a 50-million-barrel proposal discussed earlier. Brent held near $105, and the reason may be that traders already expected both.
Two of the cushions oil traders had been counting on this month thinned out in the same week. The price of Brent crude hardly reacted.
Oil flows through the Strait of Hormuz averaged 11.62 million barrels a day in the week to Oct. 13, according to ship-tracking firm Kpler, against a baseline of 17.15 million barrels. That is a shortfall of about 5.5 million barrels a day, or 32%. The same firm's data had shown Middle East crude exports running above prewar levels on some days in late September. The two figures measure different things, one total exports and the other transits through the Strait, so the new number does not cancel the old one. But it undercuts the idea that Gulf supply was steadily normalizing.
The stockpile release came in small
On Thursday the International Energy Agency's member countries agreed to speed up the release of the remaining emergency stocks they pledged in March, "including over 20 million barrels of diesel as soon as possible." About 330 million barrels have been released so far of the more than 400 million promised.
Just over 20 million barrels is well below the 50 million barrels of diesel that members had considered earlier, according to a person familiar with the discussions. Washington informally pressed for at least 100 million more barrels, according to people familiar with the matter. Gasoil futures in London ticked up after the announcement to $1,430.75 a ton. Ole Hansen of Saxo Bank described the reaction as "some disappointment."
A third source of supply is under pressure. Ukraine resumed strikes on Russian refineries this week, hitting a Rosneft plant in Ryazan, after President Volodymyr Zelenskiy declared an end to a brief pause in energy attacks.
The price
Brent traded near $105.11 a barrel early Friday, down slightly on the session and within the roughly $104-to-$107 range it has held since Oct. 8, after trading near $100 in the first week of the month. U.S. crude settled more than 3% higher on Thursday after government data showed an 8.6 million-barrel drop in commercial inventories, while Brent finished little changed. Heating oil futures were near $4.59 a gallon.
Analysts at ING said the market is "pricing in a significant risk premium" and that removing it entirely would take "some kind of agreement between the US and Iran." Hansen took a calmer view of the physical market, saying "we are not dealing with any shortages as such."
Market implications
One reading is that the physical market is tightening again and the premium is too small. Transits are down by a third, the diesel release is less than half the size discussed, refinery strikes have resumed and Washington is still asking allies for more barrels. Diesel is the tightest part of the barrel, and it feeds most directly into freight costs and producer prices, which rose 1.3% in September.
A second reading is that the price already reflects all of it. Brent has held above $100 all month, about 330 million barrels, more than three-quarters of the reserve oil now planned, has already been released with about 100 million still to come, and President Trump has predicted that oil "will go dropping like a rock" once the conflict winds down. On that view, a flat price in a bad-news week is a sign of how much risk traders have already paid for.
What to watch
Next week's tanker-transit figures, the pace of IEA diesel deliveries, and ICE gasoil cracks, which would widen first if the diesel shortfall bites. A Brent break above $107 on weaker flows would suggest the premium is being rebuilt; a break below $104 would suggest traders are looking past the Strait.