A four-store Atlanta hardware chain that nearly failed to complete its own IPO in 1981 has quietly outrun every stock in the S&P 500, including the technology names investors credit with the market's modern gains.
Home Depot went public on , and the offering barely happened. The company, then a four-store hardware chain based in Atlanta, had exhausted its loan capacity and turned to the public market as a last resort. Bear Stearns agreed to underwrite a planned $6 million offering only because Ken Langone, a well-connected investment banker who also sat on Home Depot's board as a nonexecutive co-founder, called in favors to make it happen. Demand was thin enough that Bear Stearns nearly walked away a week before the deal, and when the offering finally went out, it raised just $4 million at an initial market capitalization under $40 million.
Forty-five years later, that unlikely IPO has produced the single highest total return of any stock in the S&P 500. A $1,000 investment in Home Depot on the day of its offering, with dividends reinvested, would be worth roughly $16 million today. Apple's IPO, which came less than a year later, turned the same $1,000 into about $4 million, a fraction of Home Depot's return despite Apple's far larger current size. Home Depot's market capitalization today is around $300 billion, on annual sales of about $165 billion, a figure that exceeds half of Costco's total revenue while Home Depot sells essentially one category of goods.
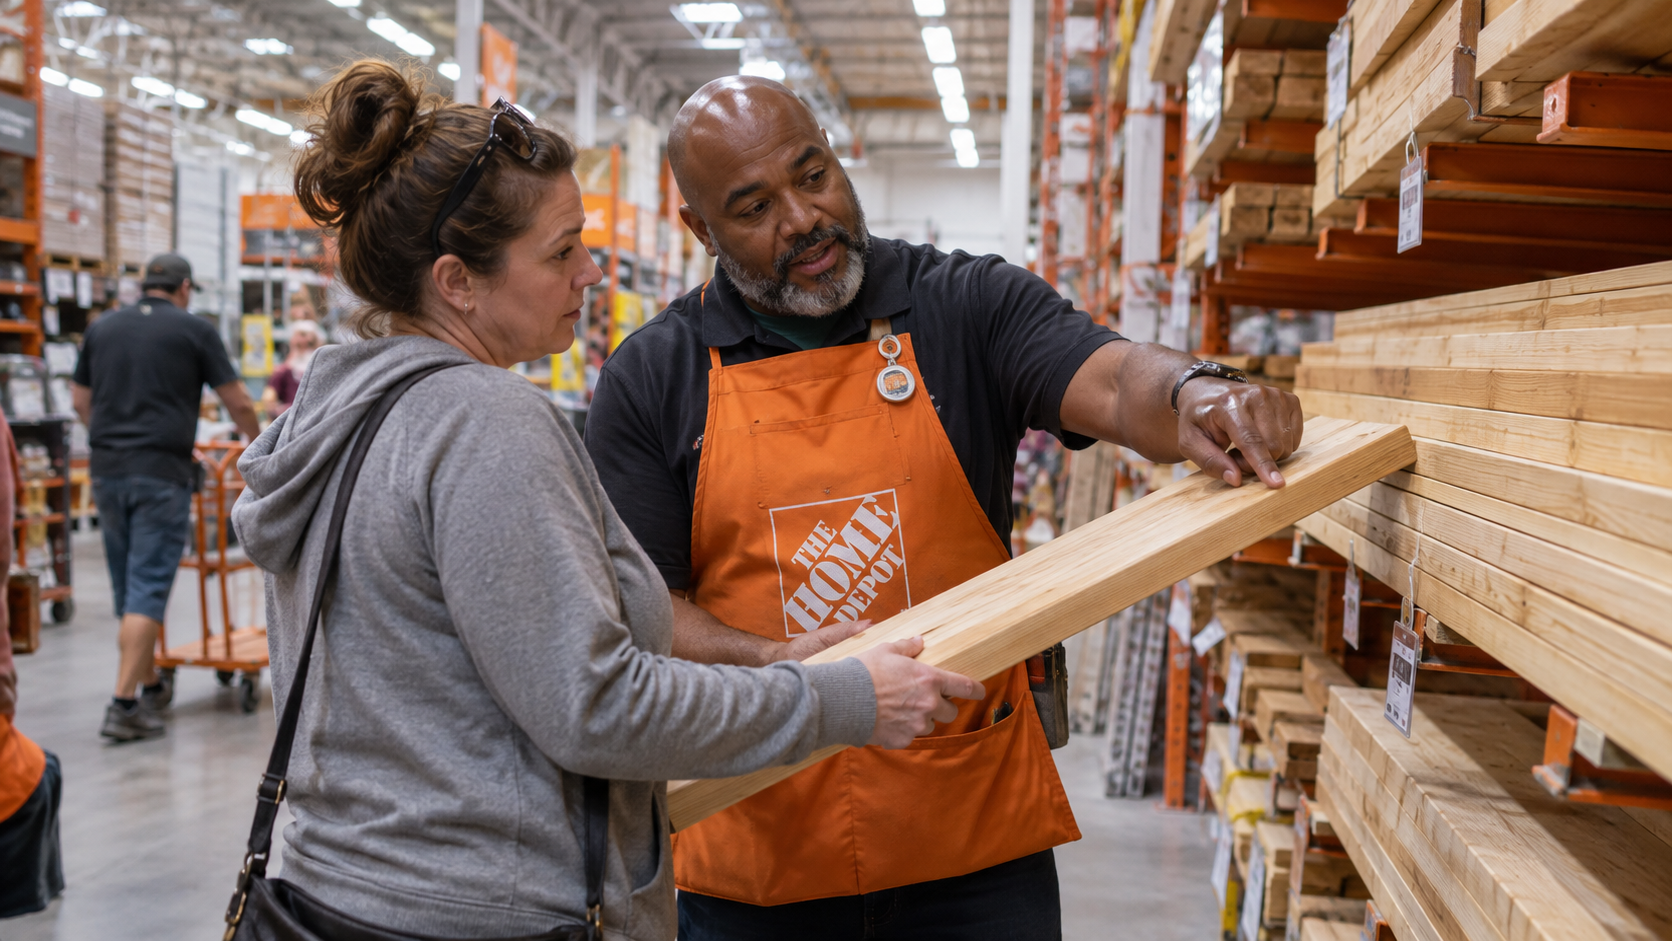
The gap between Home Depot's low starting valuation and Walmart's, which was already valued above $1 billion in 1981 on the promise of selling everything to everyone, is part of the story, but it is not the whole explanation. Home Depot's founders, Bernie Marcus, Arthur Blank and Pat Farrah, built the business around a specific insight: customers did not want power saws and lumber for their own sake, they wanted a finished deck and the confidence to build it themselves. The company staffed its stores with former tradespeople, carpenters, plumbers and electricians who could stop restocking shelves to walk a customer through a project, and it distributed equity widely among its own store employees from its earliest days, an idea borrowed from Sam Walton at Walmart.
That equity distribution became a flywheel. Frank Blake, Home Depot's chief executive from 2007 to 2014, has said the clearest sign of a store's health was seeing the company's own stock chart posted in the break room, because employees understood that time spent helping customers translated directly into sales growth, a rising share price, and their own net worth. According to Langone, roughly 3,000 store-floor employees became multimillionaires through their Home Depot equity. By 1986, five years after the IPO, the company passed $1 billion in sales and its stock had risen tenfold. By 1991, sales had passed $5 billion and the company's market value had reached $8 billion, 250 times its debut valuation a decade earlier.
Home Depot's stock has been largely flat over the past five years while technology names drove most of the market's gains, a reminder that the compounding behind this record was built over four and a half decades, not the last several years. For investors weighing where durable, decades-long value creation has actually come from, the answer running through Home Depot's history is not a single breakthrough product but a business model, tradespeople-turned-salespeople, employee ownership, and a market with effectively no ceiling on how much a homeowner might eventually spend, that took years to compound into the market's best-performing stock.