
TQ Morning Briefing
Schneider Electric agreed to buy PTC for $22.6 billion at a 42% premium. Bolsonaro leads Brazil's first round and markets surged. The euro hit its lowest since May 2025. Futures are near flat.
France Is Still Breaking. Brazil Is Racing the Other Way.
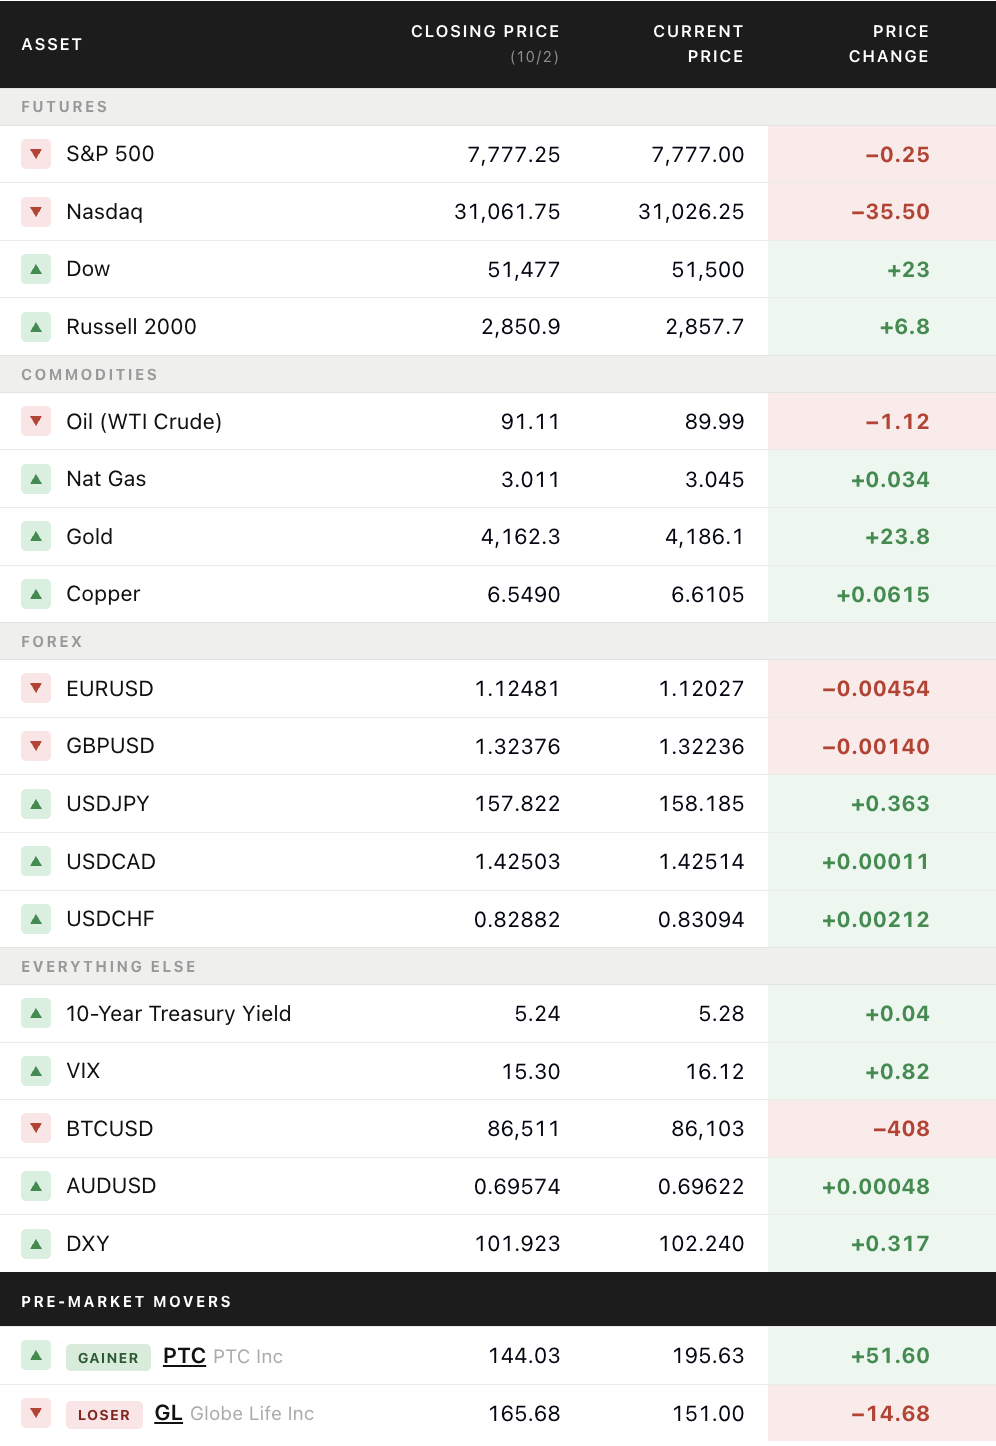
S&P futures are near flat. Nasdaq futures are down slightly. The 10-year yield holds at 5.273%. WTI is down about 1% to near $90.
France's bond yields are back at 2002 highs. The cost of insuring against a French default nearly doubled in two weeks. The euro fell to its lowest since May 2025. Spain called a snap election for November 29.
Goldman's Anthony Gutman told CNBC this morning that governments need to cut spending to bring borrowing costs under control.
The US session opens with a two-speed world. European credit risk is tightening. Brazilian risk appetite is expanding. The dollar is strengthening against both.
Market Implication
Watch the France-Germany bond spread today. Last week it hit levels not seen since 2012. If it widens past 1.5 percentage points again, European bank stocks and the euro are the first to price how far the pressure spreads.
Investing In The Titans of AI
Carnegie didn't invent steel. He used new technology to produce it cheaper and faster than anyone on Earth.
Rockefeller didn't discover oil. He used industrial machinery to refine it more efficiently.
Vanderbilt didn't build the railroad. He understood that whoever controlled the infrastructure controlled the economy.
Their combined fortunes were between $700 billion and $1 trillion.
Best-selling financial author Alexander Green has identified three companies positioned to be the Titans of the AI age.
Schneider Electric Bought PTC for $22.6 Billion. Industrial Software Was on Sale.
Schneider Electric (SU) agreed Sunday to buy PTC (PTC) in an all-cash deal at $205 per share, a 42% premium to Friday's close. The transaction values PTC at about $22.6 billion and is expected to close by mid-2027. PTC surged 35% premarket. Schneider fell about 9% in Paris.
PTC makes software that manages how products are designed, manufactured, and maintained. Schneider builds electrical infrastructure and AI data center systems. The pitch is that software running factories and hardware powering them belong under the same roof.
Citi described the deal as "opportunistic." AI disruption fears have de-rated industrial software companies over the past year. Schneider is buying into that de-rating at a 42% premium. The deal is Schneider's largest ever, funded with debt at a moment when European borrowing costs are rising.
Structural Setup
PTC's 42% premium sets a reference price for the industrial software category. Watch Autodesk (ADSK) and Ansys (ANSS) this week. If they move on the PTC news, the market is pricing a broader takeout wave. If they don't, the deal stays company-specific and the de-rating holds for everyone else.
Brazil Voted. Bolsonaro Is Leading. Markets Bought It Before the Runoff.
Bolsonaro took about 47% of Sunday's first round against Lula's roughly 45%. Neither crossed 50%. The runoff is October 25.
The market's first move was immediate.
EWZ jumped more than 11% premarket. Itau Unibanco (ITUB) and Banco Bradesco were both up more than 12%. Nu Holdings (NU) and XP (XP) also surged.
Markets are reading a potential Bolsonaro government as more aligned with Washington, friendlier to capital, and more supportive of market-oriented reforms.
The margin is narrow. Three weeks remain. Whether the first-round read holds depends on an election that has not happened yet.
The Closest Thing to a Virtual AI Monopoly Wall Street Is Ignoring
A little-known company is building what may be the closest thing to a virtual monopoly the AI era has ever seen.
Only 3...
Yet it beat Apple, Amazon, and the S&P 500 combined...
While paying out $146,000 in total dividends on a 1,000-share stake.
Kevin O'Leary calls what it controls a "unicorn."
Right now, it's trading at a rare discount.
>>>Whitney Tilson reveals the name, completely free.<<<
This ad is sent on behalf of Stansberry Research, 1125 N Charles St, Baltimore, MD 21201. If you would like to optout from receiving offers from Stansberry Research please click here.
The October 25 runoff is the real trade, not the first round. Watch the Brazilian real alongside EWZ this week. If the currency appreciates alongside the ETF, foreign institutional capital is taking a position. If EWZ runs while the real stays flat, the rally is domestic and speculative.
Intel Fell on a Musk Post. Teralab Is Talking to TSMC.
Intel (INTC) fell nearly 4% premarket after Elon Musk posted on X over the weekend confirming that his chip venture Teralab was in talks to work with Taiwan Semiconductor Manufacturing (TSM). TSMC rose about 3% in Taiwan.
Teralab is Musk's AI chip startup. A Teralab partnership with TSMC directly reduces the odds that it uses Intel's foundry services. Intel has been building its foundry business as an alternative to TSMC, pitching US-based chip production to AI customers who want supply chain diversity.
Losing a potential customer before the relationship was formally announced is a specific kind of negative. It is not a miss on guidance. It is a signal about where the AI chip infrastructure is routing itself.
TQ Edge Setup
Watch Intel's next earnings call for foundry business commentary. The Teralab-TSMC news is one data point, but it lands after a stretch in which Intel was positioning its foundry as the US-based alternative. If AI customers route foundry relationships to TSMC anyway, Intel's foundry thesis needs a new anchor.
Middle East Conflict Lights Fuse on US Debt Bomb
America was already drowning in $38 trillion of debt, but the recent conflict in the Middle East just accelerated the timeline.
As oil spikes, a 100-year-old stock market signal that accurately predicted the 2008 and 2020 crashes is flashing a massive "Sell" on dozens of popular U.S. equities.
If you hold the wrong stocks when this debt crisis hits, it could wipe out years of gains.
Click here to see the 10 popular stocks to dump immediately
11780 US Highway 1, Palm Beach Gardens, FL 33408-3080 Would you like to edit your e-mail notification preferences or unsubscribe from our mailing list? Copyright © 2026 Weiss Ratings. All rights reserved.
Fertilizer Shortages Are Building. 80% Cereal Price Increases Are on the Table.
About one-third of global fertilizer shipments transit the Strait of Hormuz. Since the war began, available fertilizer capacity has fallen nearly 40%, according to the International Chamber of Commerce. ICC Secretary-General John Denton estimated cereal prices could rise up to 80% if Hormuz stays closed.
The G7 released 100 million barrels of oil last week. No equivalent response exists for fertilizer.
Aramco CEO Amin Nasser added context at the Energy Intelligence Forum in London this morning. He said global oil stocks are at stress levels and only about 10% can actually be accessed quickly.
Just replenishing strategic reserves to prewar levels would add 2 million barrels per day to global demand for 18 months once the conflict ends. The restocking wave follows the war. It does not coincide with it.
Iran's parliament speaker reiterated over the weekend that Hormuz would not reopen until Iran's conditions were met.
The Read
The G7 addressed the immediate supply crunch. It did not address the fertilizer chain or the demand surge that follows a resolution. Watch corn and wheat futures this week. Fertilizer scarcity feeds into crop prices with a 3 to 6 month lag. If staple commodities start moving now, the food inflation signal is already running.
Economic Data: ISM Services PMI today
Fed Speakers: Vice Chair Bowman, Dallas Fed's Logan, NY Fed's Williams all speaking Tuesday
Fed Watch: September meeting minutes released Wednesday | 10-year auction Wednesday | 30-year auction Thursday
Earnings: PepsiCo (PEP) Thursday | Delta Air Lines (DAL) Friday
Overnight: Nikkei +2.4%, mainland China and South Korea closed, Stoxx 600 +0.5%
The week opens on three fronts at once.
Schneider paid a 42% premium for a category AI is reshaping, with its own borrowing costs rising. Brazil's markets treated a first-round lead as a verdict before the runoff. France's credit default swap costs doubled in two weeks while its government figures out how to fund next year.
The dollar is near an 18-month high. The euro is at a 17-month low. The 10-year is at 5.27%.
Fed minutes land Wednesday alongside the 10-year auction. PepsiCo reports Thursday as the first major consumer read of the quarter. Delta follows Friday with the first airline comment on fuel costs after the G7 release.
Last week ended with a soft jobs print that gave the market one clean session. This week opens with a fiscal story, a political story, and a food supply story that nobody has run a coordinated response to yet.
3 Market Signals Most Investors Aren't Watching
The headline is usually the last place the story shows up.
By the time everyone is talking about a stock… the signals underneath it may have been changing for weeks.
• Institutional money moves.
• Options activity changes.
• Management confidence shifts.
• Fundamentals improve, or quietly begin telling a different story.
That’s exactly what our analysts found in three stocks where the evidence stopped agreeing with itself.
And in all three cases, the story is still developing.