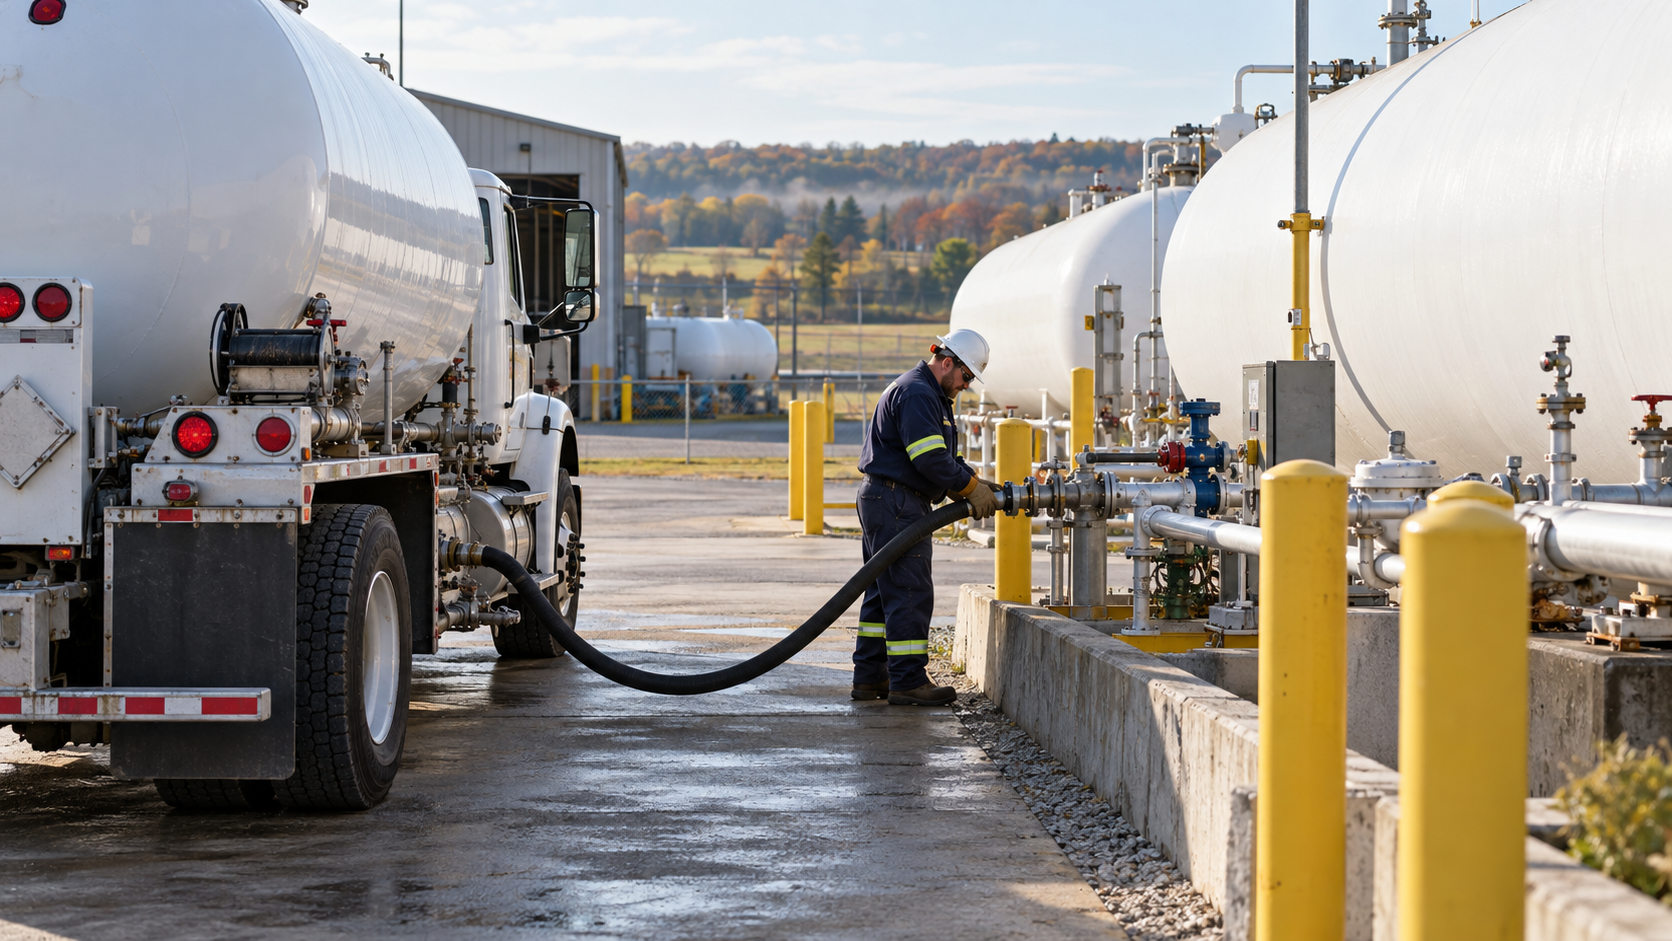
Platinum Equity agreed to buy EDP, a U.S. propane distributor, with Oaktree joining three banks in the financing. Industrial Growth Partners agreed to sell AdvancedPCB, a maker of circuit boards for defense and aerospace, to Amphenol. Terms of both were undisclosed.
Private-equity firms were on both sides of the industrial deal market this week, one buying and one selling. Both deals show where the money is coming from and where it is going.
Platinum buys EDP
Platinum Equity signed a definitive agreement to acquire EDP, a U.S. propane distributor that serves more than 200,000 customers from more than 60 locations in 24 states. Financial terms were not disclosed, and the release did not name the seller.
The financing is the notable part. J.P. Morgan, Guggenheim, Oaktree and Fifth Third arranged it. Oaktree is a private credit manager, not a bank, and its place alongside traditional lenders shows direct lenders taking a seat in bank-led buyout financing. Sometimes they are the only source. This week, funds managed by Apollo committed all of the debt and preferred equity behind Thrive Holdings' $10-a-share purchase of ADT.
IGP sells to Amphenol
Industrial Growth Partners agreed to sell AdvancedPCB, which makes printed circuit boards for defense and aerospace customers, to Amphenol. Terms were not disclosed, and the sale requires U.S. regulatory approval.
That is a sale from a financial owner to a strategic buyer. It fits a broader pattern: EY said private-equity exits outpaced acquisitions in the third quarter.
It is also the second aerospace supplier to agree to a sale in days. On Wednesday, infrastructure investor I Squared Capital agreed to buy Orizon Aerostructures, citing contracts that run for the life of aircraft programs.
What the silence costs
Neither deal came with a price, so investors cannot see the multiples paid. For EDP, the debt package will eventually show how much leverage the buyer is using. For AdvancedPCB, any Amphenol filing may reveal the value.
Healthy flow or selective market?
The healthy view: sponsors are both buying with committed financing and selling to strategic buyers, and private lenders are sharing deals with banks.
The selective view: both assets are in favored niches, defense and steady cash-flow distribution, and two undisclosed deals say little about how sponsors are faring with everything else they need to sell.
What to watch
Disclosure of terms in any filings, the regulatory review of the Amphenol purchase, the closing of the EDP deal, and whether more private credit managers join bank-led buyout financings.