
TQ Morning Briefing
Nike guided for more sales declines and flagged China. The US is sending a third carrier to the Middle East with 10,000 troops. Europe held an emergency meeting to release diesel reserves. WTI is down nearly 4%. The jobs data this morning is set to test the rate narrative.
Oil Is Falling. Futures Are Rising. The Two Are Reading the Same News Differently.
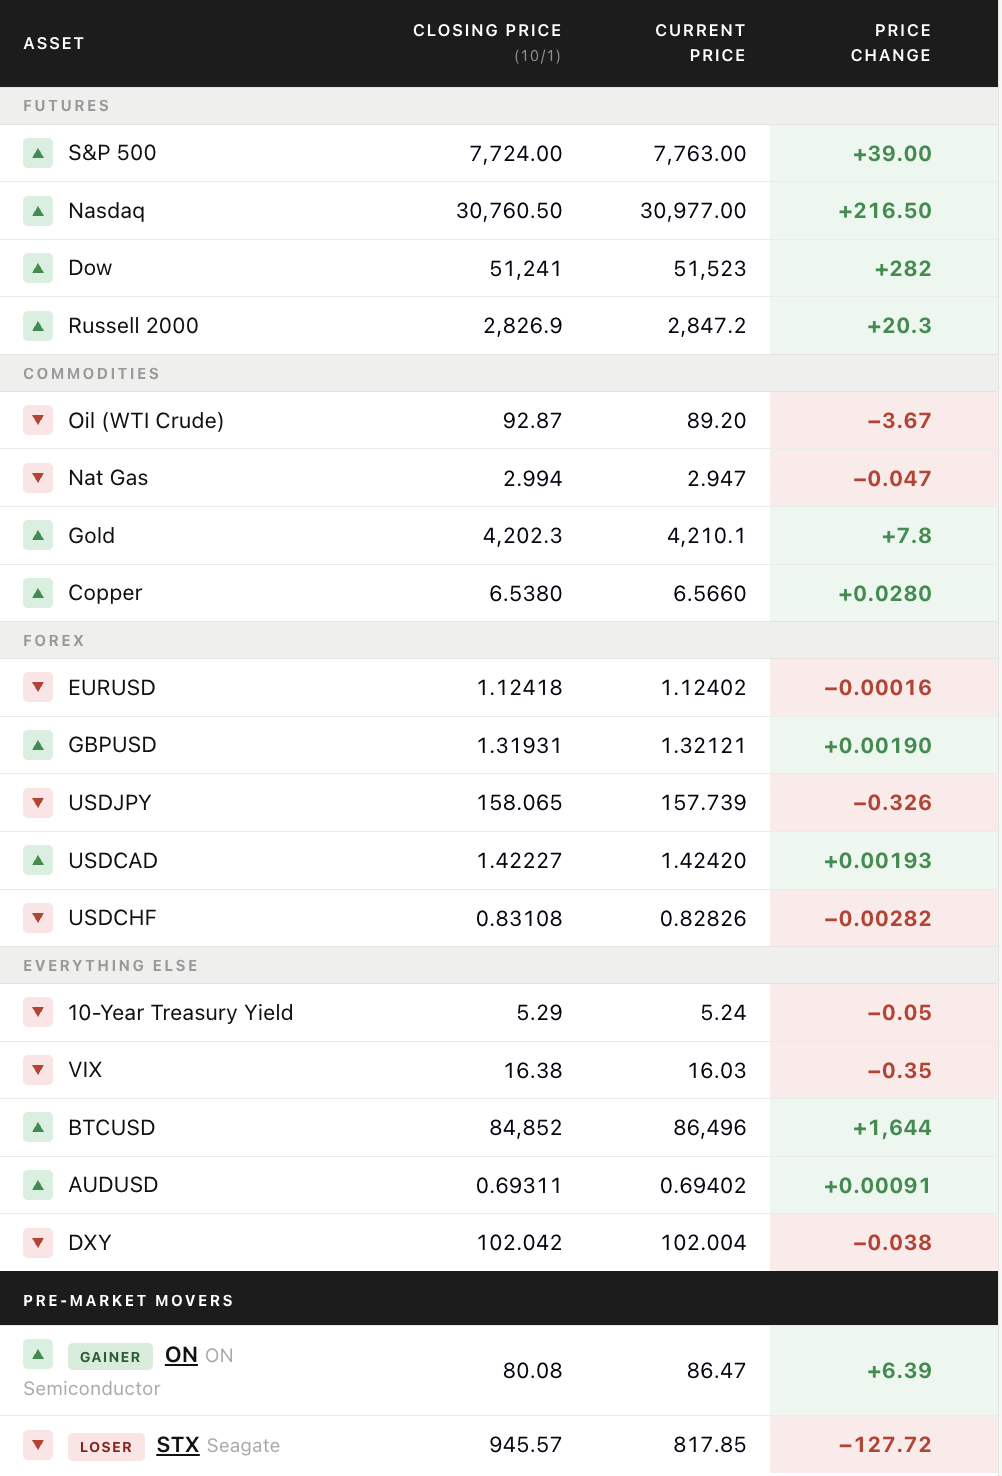
S&P futures are up 0.5%. Nasdaq futures are up 0.7%. WTI is down nearly 4%, below $89.30.
Europe held an emergency meeting this morning to discuss releasing strategic diesel reserves after Trump raised the prospect of banning US diesel exports. The European diesel benchmark fell more than 4%. That is pulling WTI lower.
At the same time, the US is sending a third aircraft carrier strike group to the Middle East, with up to 10,000 additional troops. The carrier arrives by the end of November. Trump already said last weekend that he expects strikes on Iran to resume after November 5. The military is moving into position.
The France-Germany bond spread crept wider overnight to 1.5 percentage points. Eurozone inflation came in at 3.8% for September, its highest in three years and above the 3.6% forecast. The 10-year is at 5.225%.
Market Implication
Equities are up on the diesel relief. Bonds are stable. The carrier deployment adds a military risk premium that crude oil has not priced yet. If the reserve release is confirmed and supply increases, the diesel trade has a ceiling. If the third carrier signals escalation rather than resolution, crude catches up later. Meanwhile, markets are also looking ahead to today’s US jobs report, with the September nonfarm payrolls (NFP) print likely to set the next move in rates and the dollar. The two are on separate clocks this morning.
The Iran War Didn't Just Make Headlines.
It broke the gold market wide open.
Investors are racing into the one asset Wall Street can't print.
But the metal isn't where the real money gets made.
There's one tiny company sitting on more gold than France, Italy, and China combined.
It moves 10x faster than the metal — and it's still trading at a 99% discount to what it's actually worth.
The ticker is waiting for you.
Get the full gold briefing — including the stock name and buy-up-to price
Nike Guided for More Declines. China Is Specifically Getting Worse.
Nike (NKE) fell about 9% in premarket after reporting fiscal first-quarter results that missed and guiding for continued revenue declines this fiscal year. CEO Elliott Hill singled out China, Nike's second-largest market, as the specific drag. Sales in Greater China fell again.
China has been a problem for Nike for four straight quarters. Local brands like Anta and Li-Ning have taken share. A prior boycott over Nike's stance on Xinjiang supply chains left lasting damage in the market. The guidance for continued declines means Nike is not calling a bottom.
Volvo Cars (VOLCAR) pulled its full-year guidance before the open for the same reason. Greater China sales fell 41% in the third quarter. The company had unveiled 13 new models at an event last month with plans to double its market share. The guidance withdrawal landed before that strategy had a chance to show up in numbers.
Two global consumer brands, one American and one Swedish, flagging China in the same premarket window is not noise. It is a consistent signal about what is happening to foreign consumer brands in the world's second-largest economy right now.
The China consumer signal from Nike and Volvo is the early data point for a long list of earnings reports ahead. Starbucks (SBUX), Tapestry (TPR) and Estee Lauder (EL) all carry China exposure. If their October commentary echoes Nike's, the story has become a sector position, not a company-specific one.
What is Elon Building in Texas?
Elon's mysterious Texas project will be 3X the size of Central Park… Cost $122 billion to build… And singlehandedly DOUBLE American chip production. One investment (not Tesla/SpaceX) is at the center of it all.
Click here to get its name and free ticker.
This ad is sent on behalf of InvestorPlace Media at 1125 N. Charles Street, Baltimore, Maryland 21201. If you're not interested in this opportunity, pleaseclick here.
Europe Is Releasing Diesel Reserves. The G7 Is Coordinating.
European officials held an emergency meeting this morning to discuss releasing strategic reserves after Trump said Sunday he was "very seriously" considering a US diesel export ban. French President Macron is organizing a G7 videoconference to coordinate on global fuel supply. France, the UK, Germany, Italy and Ireland held a separate coordination call Thursday.
Macron spoke directly with Trump Thursday and pushed for a joint approach to the refined product crunch. The European diesel benchmark fell more than 4% on the reserve discussion.
The US diesel export ban threat and the European reserve release are responses to the same shortage from opposite directions. The US is considering restricting exports to lower domestic prices. Europe is preparing to release supply to lower its own.
If both happen, the global diesel trade undergoes a structural shift. The same cargo does not flow from the US to Europe as freely. Diesel markets in both regions reprice off their own reserves rather than the other's surplus.
Gulf refined product exports are still at roughly half their 2025 average. Russia extended its diesel export ban through October. China reportedly paused its fuel export quota for October. That is three separate supply constraints on refined products converging in the same week.
TQ Edge Setup
Watch whether the G7 call produces a coordinated IEA reserve release or only national-level action. A joint release from multiple member countries is a larger and more durable supply intervention. France acting alone moves the benchmark for one session. A coordinated G7 release reprices the diesel trade for weeks.
A Third Aircraft Carrier Is Going to the Middle East. Troops Follow.
US officials told the WSJ that a third carrier strike group is deploying to the Middle East and will arrive by the end of November. Washington is also sending up to 10,000 additional troops on the same timeline.
Two carriers are already in the region. A third brings the US naval presence to its largest concentration in the Middle East in years. Trump told aides last weekend he expects strikes on Iran to resume after the midterm elections on November 5. The third carrier arrives shortly after that window opens.
The military posture is consistent with a planned escalation rather than a deterrence deployment. Deterrence deployments tend to arrive fast and are announced early. This one is scheduled, sized, and timed to coincide with the post-midterm diplomatic calendar Trump already described.
For oil, the carrier adds a conflict risk premium that the diesel reserve news is temporarily offsetting. The two are pulling in opposite directions this morning. One eases the refined product crunch. The other raises the probability of a larger military engagement that tightens crude supply further.
Watch Signal
Watch crude oil separately from the diesel benchmark today. If WTI holds its decline despite the carrier news, the market is pricing diplomatic resolution ahead of escalation. If crude reverses higher while diesel stays lower, the market is separating the two stories and pricing conflict risk on crude while relief flows through refined products.
Trump to build "biggest data center on the planet"
America's about to get its first national data center… Completely funded by taxpayer dollars. When it comes online just days from now… This device could change the history of Artificial Intelligence… And even human civilization. (It could also make early investors in this company very happy.) Louis Navellier believes it will secure America's dominance over China in the AI arms race… While completely sidestepping the dangers of Artificial Superintelligence. Donald Trump committed $1 billion to support the stock behind the coming breakthrough right now… Ahead of a potential announcement from the company that could hit soon. Get all the details – down to the company name and ticker – here, in Louis' brand-new presentation.
This ad is sent on behalf of InvestorPlace Media at 1125 N. Charles Street, Baltimore, Maryland 21201. If you're not interested in this opportunity, pleaseclick here.
Economic Data: No major US data today
Fed Speakers: Dallas Fed President Logan speaking today
Earnings: Nike (NKE) results are out | No other major US earnings
Key Watch: G7 diesel coordination call expected | Third carrier deployment confirmed
Overnight: Nikkei -0.94%, Kospi +0.46%, Stoxx 600 +0.76%, WTI -3.85%
Nike Said China Is Getting Worse. The US Is Moving a Third Carrier in. Europe Is Opening Its Reserves.
Three stories before the open and none of them has a clean read.
Nike's China warning lands before a wave of October earnings from companies with the same exposure. The carrier deployment is timed to the post-midterm window Trump already described. The diesel reserve release eases one supply constraint while three others are still active.
And then there’s today’s US jobs report. The NFP print could reset the rate and dollar narrative just as markets are trying to price the impact of the oil shock.
WTI is down nearly 4% on the diesel news. Futures are up on the rate stability and the reserve relief. The bond market is holding at 5.22% on the 10-year, which is not a signal that anything structural has changed.
The soft signals are moving today. Oil down, futures up, Europe coordinating. The hard ones are still in the same place they were Thursday morning.
3 Stocks at a Major Turning Point
Something unusual is happening beneath the surface of three widely followed stocks.
In each case, the fundamentals are saying one thing... while institutional activity, management signals or the options market are saying something else.
That kind of disagreement can matter.
Because when the evidence stops lining up, the next move in the story often comes down to a handful of signals most investors never think to watch.
Our new FREE Market Tell Special Report breaks down three of these situations, and shows you exactly what we’re watching next.