The battery storage company's second downward revision this fiscal year has triggered a wave of price-target cuts even as management insists demand remains strong.
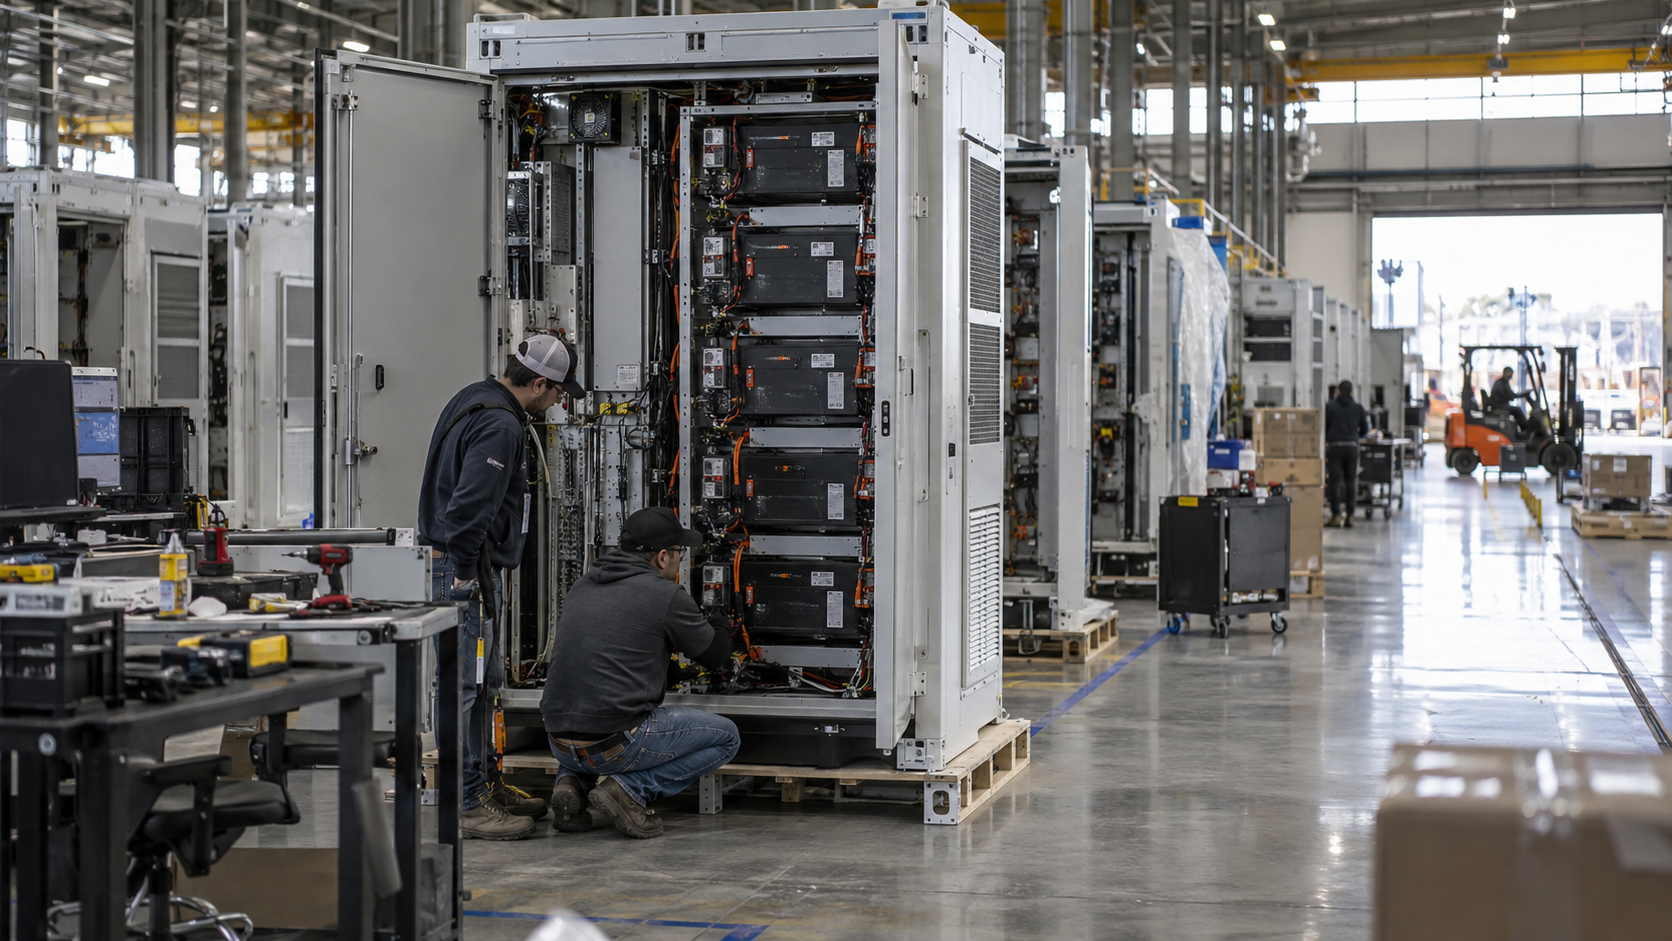
Fluence Energy has cut its fiscal 2026 guidance for the second time this fiscal year, and the scale of the revision has rattled Wall Street. The company now expects revenue of about $2.4 billion, down from a prior midpoint near $3.0 billion, and an adjusted EBITDA loss of about $200 million, compared with a prior guide of roughly a $10 million loss. That is a roughly twentyfold widening of the expected loss. Fluence attributed the cut to continued ramp-up delays at its contract-manufacturing facility in Houston, Texas.
The company announced the revision on September 16, paired with a same-day conference call and the naming of a new Chief Operating Officer. The stock fell sharply in after-hours trading and kept declining over the following two sessions, closing around $7.22 on September 18. That marks a cumulative drop of roughly 20% from a pre-announcement close near $9.05, and it leaves the stock trading near the bottom of its 52-week range of $7.01 to $33.51.
Wall Street's response was swift. At least six firms cut price targets or ratings within 48 hours. JPMorgan moved to Neutral with an $8 target. RBC Capital cut to Sector Perform at $4. BMO Capital moved to Market Perform at $7. Jefferies downgraded the stock to Hold at $7. Baird downgraded to Underperform at $3. A sixth firm modeled a need for roughly $150 million in new debt financing in fiscal 2027, a notable sum against a market capitalization of roughly $1.5 billion, and does not expect the company to reach adjusted EBITDA breakeven until fiscal 2028.
The tension in the story is stark. Fluence's own release said demand "remained strong both domestically and internationally" and that its international supply chain "continued to work well." The company points to a backlog of roughly $2.9 billion as evidence that its underlying business remains intact. Wall Street's counterargument is written into the stock's valuation: shares now trade at roughly 0.4 times sales, well below the company's historical median of about 1.0 times, a gap that reflects skepticism about execution rather than about demand.
This is the second guidance cut of Fluence's fiscal year. The company started the year projecting a profit, then cut that to a small loss, and has now cut again to a far larger one. That progression, more than any single quarter's numbers, is what has analysts focused on execution risk and financing needs rather than the order book.
Going forward, investors will be watching whether the new COO can stabilize the Houston ramp, whether the $2.9 billion backlog converts into revenue on the timeline management now projects, and whether the company can avoid tapping debt markets on terms that would pressure an already-discounted stock further.