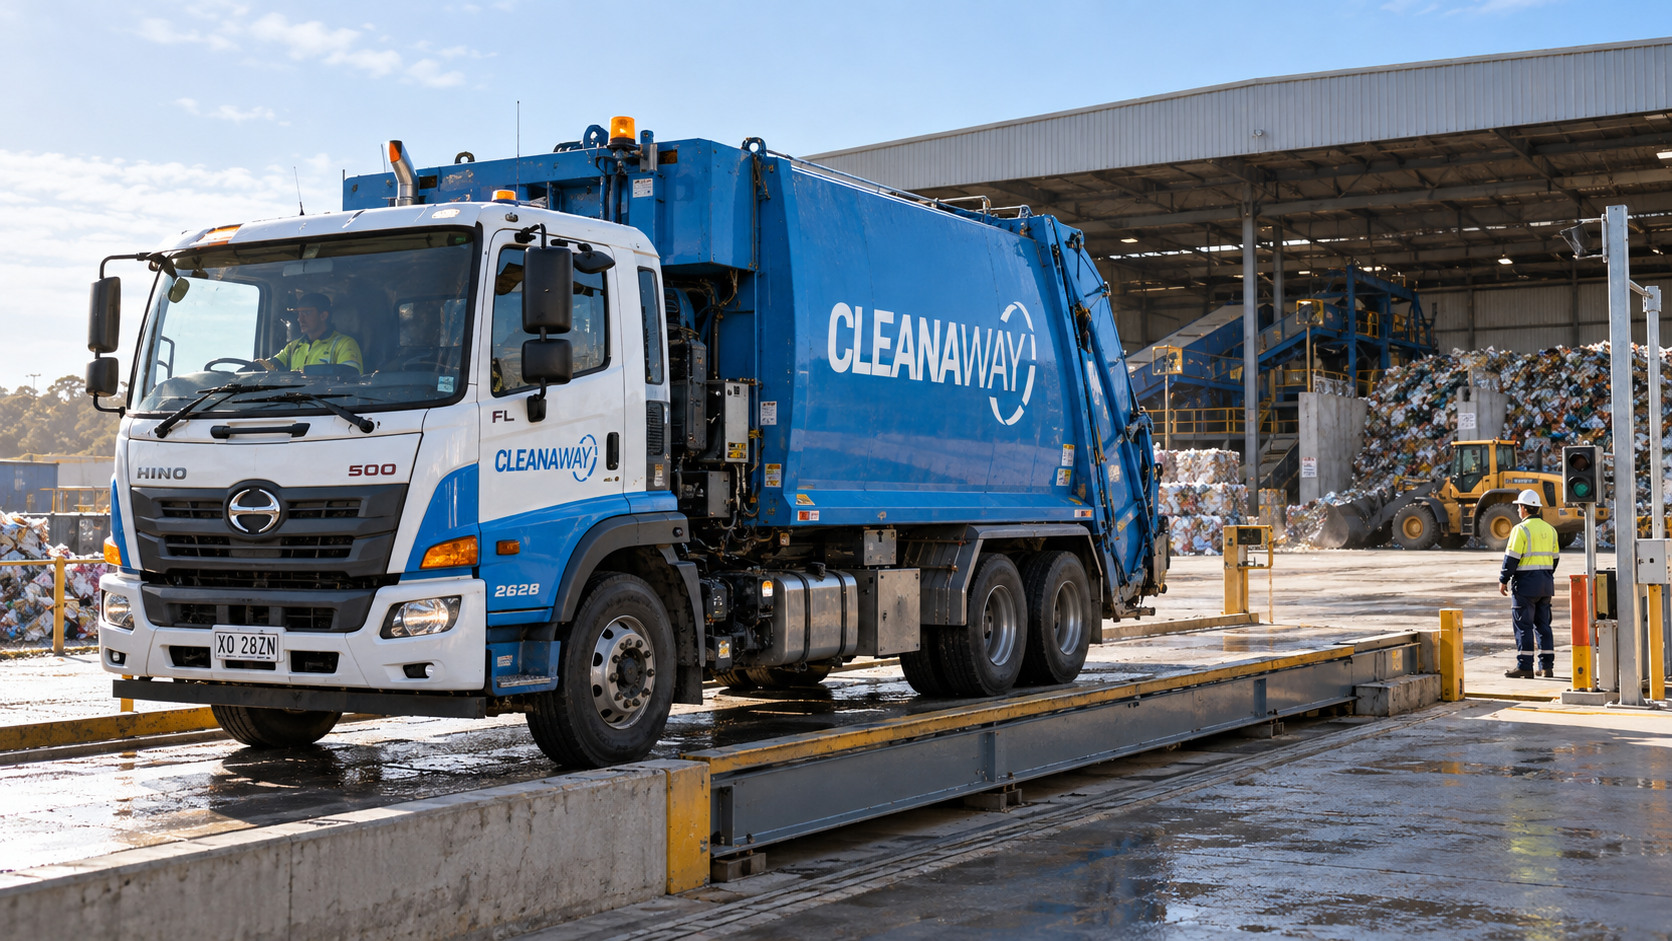
EQT Infrastructure VI signed a binding A$9.3 billion deal to take Cleanaway private at A$3.095 a share, or A$3.13 including a dividend already paid, 32.1% above the undisturbed price. The board recommends it, roughly A$5.6 billion of debt from about 20 lenders is reportedly lined up, and EQT says the fund will be 85% to 90% invested.
Infrastructure investors are still willing to pay full prices for businesses that look like utilities. Cleanaway is the latest proof.
EQT has signed a binding agreement for its Infrastructure VI fund to acquire all of Cleanaway Waste Management, the ASX-listed waste and resource recovery company, for A$3.095 a share in cash. The deal values Cleanaway at an enterprise value of about A$9.3 billion. Including the 3.5-cent final dividend paid in October, holders receive A$3.13 a share, 32.1% above the undisturbed A$2.37 close on Aug. 12, Cleanaway said. Cleanaway's board unanimously recommends the deal, subject to an independent expert's report and in the absence of a superior proposal. EQT is targeting completion by the end of March 2027.
The cash price equals the A$3.13 a share EQT proposed in August, minus that dividend. Cleanaway shares closed up 20.2% at A$2.97 on Monday, about 4% below the cash price.
The multiple
Cleanaway reported underlying EBIT of A$470.2 million for its 2026 financial year. At A$9.3 billion, the enterprise value is about 19.8 times that figure, by this publication's arithmetic. The equity value is about A$7 billion.
That is a full price for a waste company, and it reflects how infrastructure funds view the business. Cleanaway collects municipal and commercial waste under long contracts, and it owns landfills, which are hard to replicate because new sites face long permitting processes. Those features produce steady, inflation-linked cash flows of the kind infrastructure investors prize, and justify a lower cost of capital than a listed market applies.
The financing
EQT has lined up a debt package of about A$5.6 billion with about 20 lenders, The Australian Financial Review reported. That would be roughly 60% of the enterprise value, by this publication's arithmetic. Earlier this month, about 15 lenders were said to be competing to underwrite more than A$5.5 billion.
Strong lender demand matters beyond this deal. In recent weeks, AirTrunk delayed a planned Singapore REIT listing and Firmus withdrew its Australian IPO. Cleanaway shows that lenders remain eager to fund businesses with contracted, essential-service cash flows, even as appetite for more speculative infrastructure cools.
The fund
EQT said the deal will bring Infrastructure VI to between 85% and 90% invested, counting closed and signed deals and net of expected syndication. A fund that is nearly fully deployed usually means its manager will raise a successor fund soon.
Conditions include approval by Cleanaway shareholders and the Federal Court, as well as regulatory clearances. If implementation occurs after May 31, 2027, EQT will pay a ticking fee of A$0.0002 a share for each day of delay.
Market implications
One reading is that the price is justified. Waste collection and landfill ownership behave like infrastructure, and an infrastructure fund's cost of capital supports a 32% premium and a multiple near 20 times EBIT.
A second reading is that the buyer is taking on real risk with significant leverage. Cleanaway's undisturbed price reflected doubts about its capital-spending plans, debt at about 60% of enterprise value leaves less room if those plans overrun, and landfills carry long-term environmental liabilities.
The take-private also removes a listed benchmark for the sector, which makes it harder for public investors to value similar businesses.
What to watch
The independent expert's valuation range; the scheme booklet and meeting date; regulatory reviews; any rival bid; final terms of the debt package; and news of EQT's next infrastructure fund. An expert's range above A$3.095 would strengthen the case that shareholders are getting a fair price.