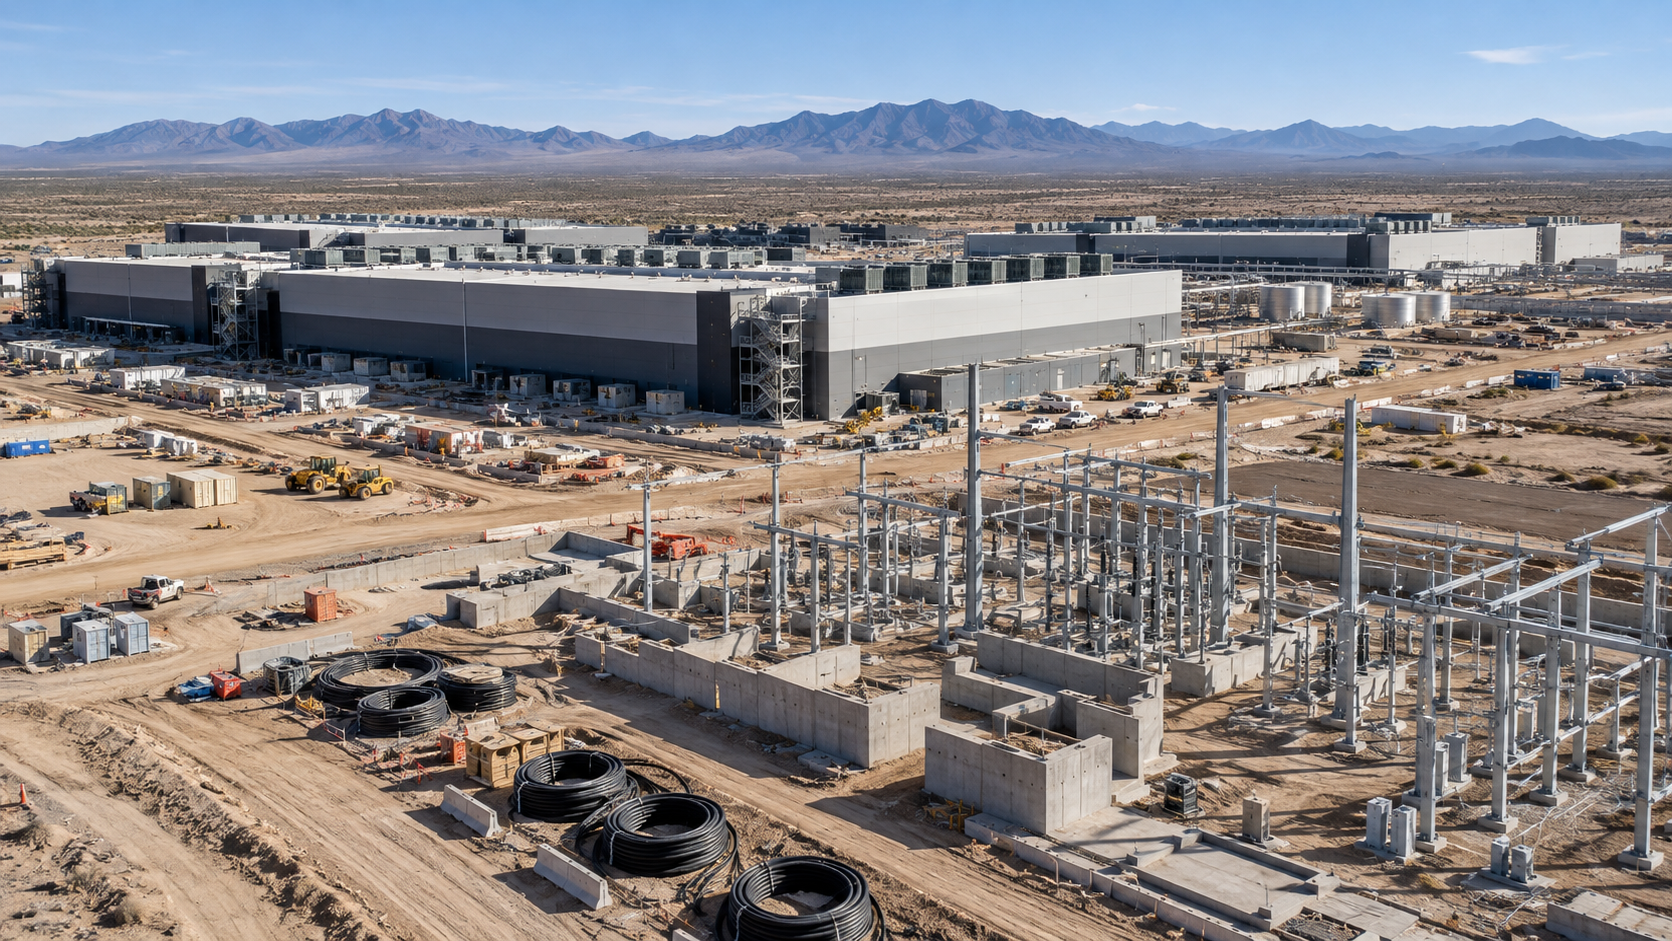
Some of the roughly $18 billion of bank debt behind Project Jupiter has recently changed hands at about 80 cents on the dollar, people familiar with the trades said. The campus's power permit hearing has been pushed to December, and Blue Owl, the developer, reports results on Oct. 29.
The price of the debt behind one of the largest privately financed AI campuses has fallen again, and the project's power problem has not been solved.
Some of the roughly $18 billion of debt tied to Project Jupiter, the Oracle-leased data-center campus in New Mexico developed by Blue Owl through its Stack unit, has recently sold at about 80 cents on the dollar, The New York Times reported, citing two people familiar with the trades. In September, the same debt was quoted at 89 to 91 cents, and at least one trade was reported below 90.
That is a further decline of roughly 9 to 11 points in about a month, by this publication's arithmetic. The size of the trades and the identities of buyers and sellers were not disclosed, and the price applies to the pieces that traded, not necessarily to the full $18 billion.
The permit slips again
The campus's power plan has suffered another delay. A New Mexico Environment Department hearing on the air permit for the project's fuel-cell microgrid will now begin on Dec. 7, replacing a previously set Nov. 23 decision deadline. A motion by the group New Energy Economy to dismiss the permit application will be heard on Oct. 26.
The buildings are near completion, with more than 4,000 construction workers on site, but they have no power. Construction of the microgrid has not started. Oracle has considered bringing in natural gas by truck, and New Mexico's attorney general has challenged the federal review of the gas pipeline meant to supply the site.
The pattern beyond New Mexico
Jupiter is not the only Oracle project whose debt is trading at a discount. Debt for Project Lighthouse, a campus in Port Washington, Wisconsin, has traded around 90 cents on the dollar or below, according to two traders. Lighthouse and a Texas campus were financed in 2025 with $38 billion borrowed from a group of banks and built with project developers; how that borrowing is structured has not been disclosed. Lighthouse was expected to be operational by 2028; one data-center research firm says a start before 2029 now looks less likely. Oracle declined to comment.
The repricing fits a wider shift in AI credit. Spreads on riskier AI-related debt have risen more than 50% over six months, according to Barclays data. The cost of insuring SoftBank's debt against default has risen above $40,000 per $1 million, from under $27,000 at the start of 2026, and SoftBank borrowed $11 billion in late September at nearly 10%.
Who absorbs the delay
Blue Owl has about $3 billion of equity in Jupiter, expected to earn about 9% during development and about 11% once the campus is complete, according to a person familiar with the project. Oracle served a force majeure notice on the project in September, which can extend the period before full rent begins. Both companies said at the time that the notice did not change their commitments.
Each delay therefore moves value in a predictable direction: away from the sponsor's step-up in returns and the banks' plans to sell down their loans, and toward the tenant's protection. A price near 80 says buyers want to be paid for that risk.
Market implications
One reading is that the discount is a technical overhang. The lease is reported to be non-cancellable, the buildings are nearly finished, and banks that could not sell their loans are paying patient credit buyers to take them. On that view, buyers at 80 cents are being well compensated for a timing problem.
A second reading is that the price reflects real completion and tenant risk. Repeated permit slippage, a force majeure notice that can delay full rent, and similar discounts on Lighthouse debt suggest the problem is structural to power-constrained AI campuses, not unique to one site.
What to watch
The Oct. 26 hearing on the motion to dismiss; any further permit delays; Blue Owl's third-quarter results and call on Oct. 29 before the market opens; any statement from Oracle on the schedule; and further trades in Jupiter or Lighthouse debt. Any disclosure from Blue Owl on Jupiter valuations would be the first official read on how the sponsor marks the project.