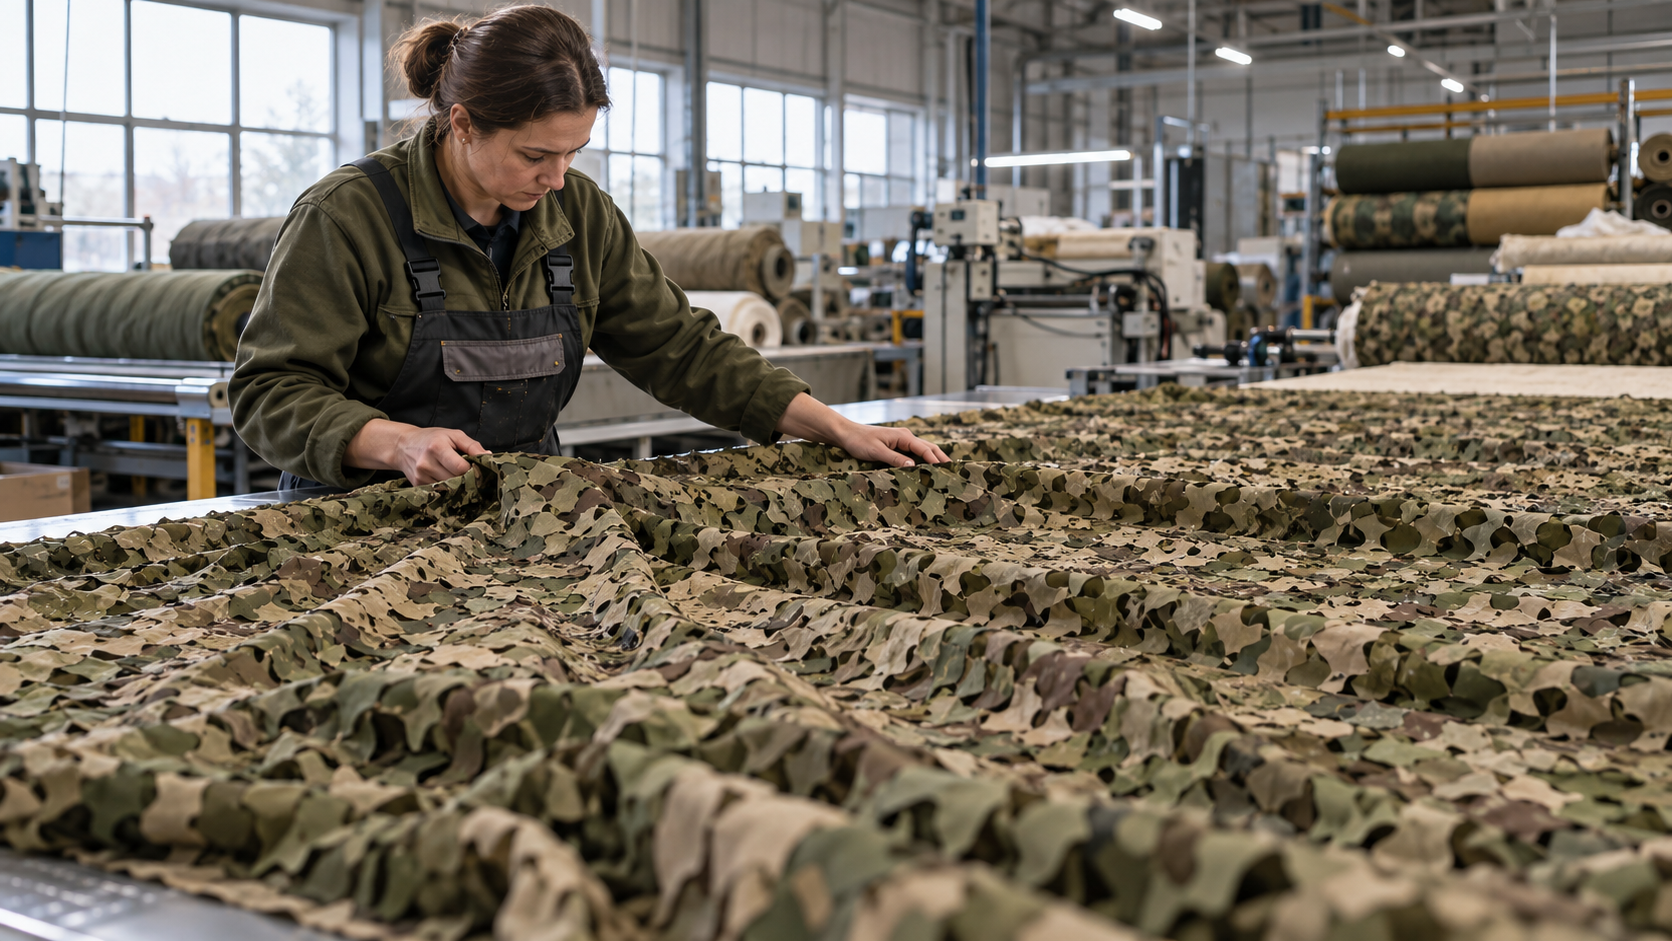
CVC's Catalyst III fund agreed to take a minority stake in Fibrotex, which sells mostly to the U.S. military. People familiar with the deal put the stake near 40% for about €250 million, below the roughly $1 billion value at which the company was marketed in April.
European buyout firms have been cautious about putting defense companies in their portfolios. CVC Capital Partners has just placed a bet, and the way it did so says as much as the deal itself.
CVC said Monday that its Catalyst III fund has agreed to invest in Fibrotex, an Israeli-American maker of camouflage and concealment systems. The Blum family, which owns the company, will keep a majority stake. Fibrotex has facilities in Kentucky and in Petah Tikva, Israel, and sells to customers in more than 20 countries. The deal requires regulatory approvals and is expected to close in the first half of 2027. Jefferies and Rothschild advised on the transaction.
The terms
CVC did not disclose the price or the size of its stake, describing it only as a minority investment. People familiar with the deal said CVC is buying about 40% of the company for about €250 million. Fibrotex's revenue in 2025 was estimated at $130 million to $150 million, most of it from sales to the U.S. military.
If those figures hold, the deal implies a value of about €625 million for the whole company, or roughly $700 million at Monday's exchange rate of about $1.12 per euro. When Fibrotex was marketed to potential investors in April, it was pitched at a valuation of around $1 billion. That suggests the buyer negotiated a discount of about 30% to the asking price, although the terms of a minority stake, including any governance rights or preferences, can make the comparison imperfect.
At about $700 million, the company would be valued at roughly 4.7 to 5.4 times its estimated 2025 revenue.
Why the structure matters
A minority stake with the founding family in control is a cautious way into a sector that can be sensitive for some of the pension funds and endowments that commit money to buyout funds.
People familiar with the matter said CVC had initially intended to inform only the investors in its funds about the deal, and that a note to those investors did not mention Israel. The firm published a short announcement on its website on Monday. The episode illustrates the balance European managers are trying to strike: demand for military equipment has risen sharply, but some of their own investors remain uneasy about the sector.
Two readings
One reading is that this marks defense becoming investable for mainstream European private equity. A large firm is committing capital to a profitable supplier whose main customer is the U.S. military, and the minority structure limits operational and reputational exposure.
The other is that the low-profile approach shows the sector remains contested. A plan to keep disclosure within the fund suggests concern about reaction, and limited partners with restrictions on weapons-related investments may push back, whatever the commercial case.
What comes next
Regulatory approvals and the closing, expected in the first half of 2027, are the formal milestones. More immediate will be whether other European firms follow with defense investments of their own, and whether any CVC fund investors object publicly.