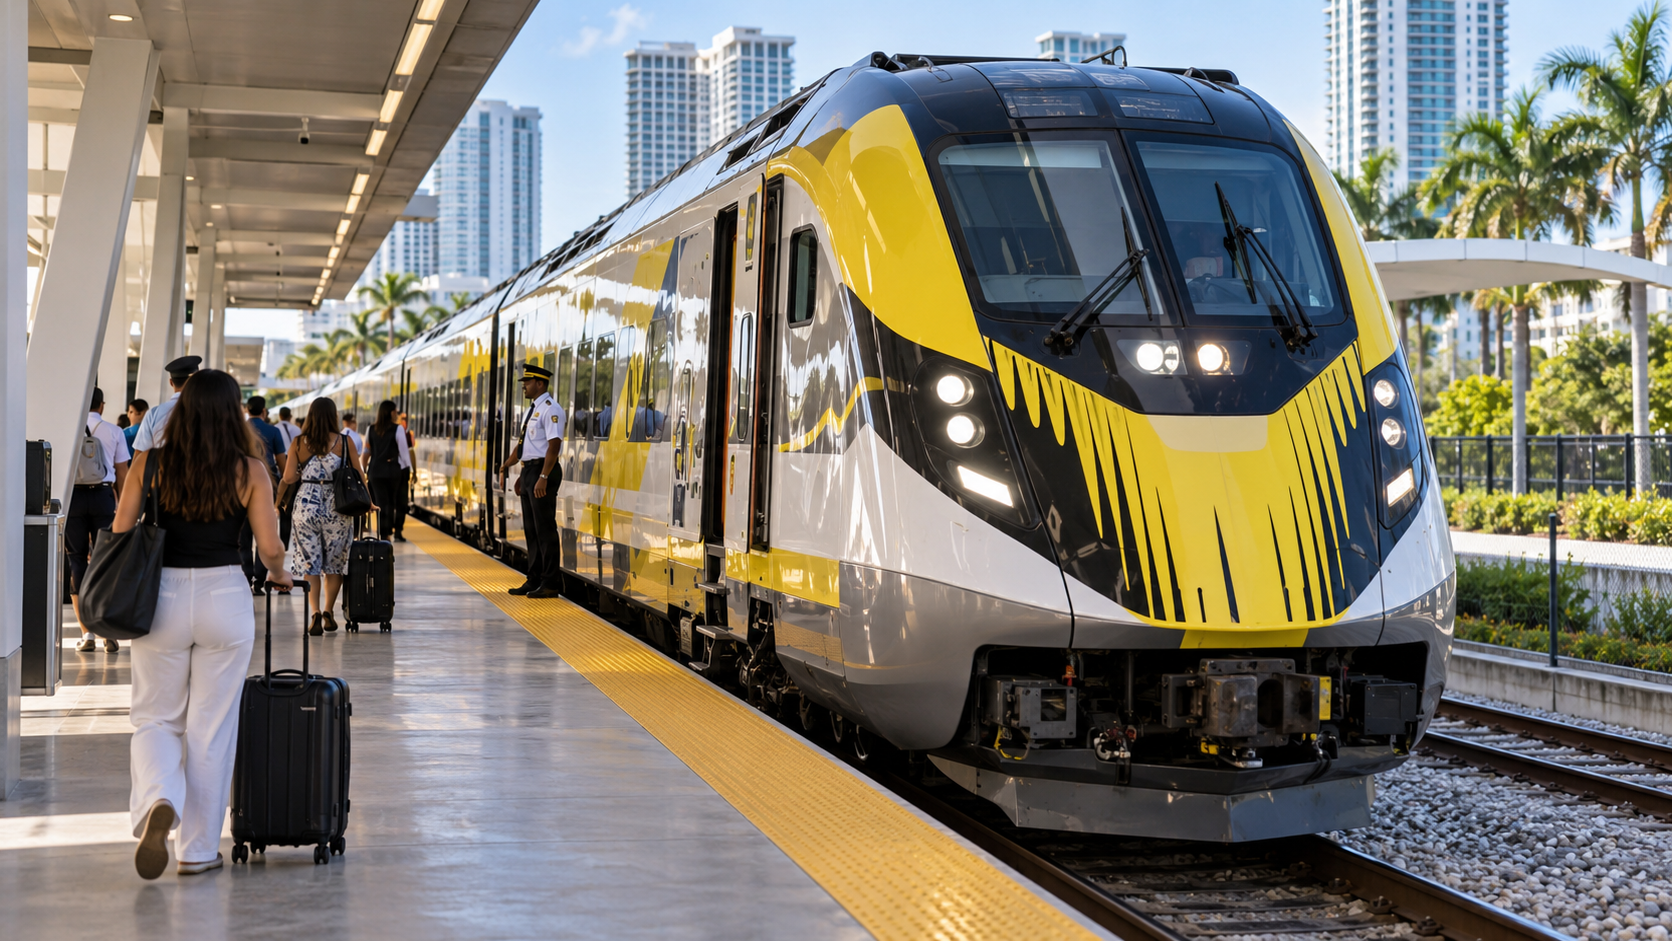
The Florida rail operator's prearranged Chapter 11 in New Jersey is designed to be quick. The harder questions are how deep the debt cut runs and how municipal bondholders fare.
Brightline, the privately owned passenger railroad connecting Miami to Orlando, has filed for Chapter 11 bankruptcy protection in New Jersey, arriving in court with a restructuring support agreement in hand and $490 million in fresh capital lined up.
The filing, made on Sept. 25, caps a long struggle to carry a debt load that the railroad's operations could not support. By entering bankruptcy with creditor support already secured, Brightline is attempting the fastest route through the process: a plan negotiated in advance, a court used mainly to confirm it, and new money to keep the trains running.
Why the structure matters
A restructuring support agreement binds a critical mass of creditors to a plan before the case begins. That shortens the time in court, limits legal fees and reduces the risk that the business loses value while stakeholders fight. It is the tool of choice for companies whose operations are viable but whose balance sheets are not.
The $490 million commitment is the other signal. Investors rarely put new capital into a bankrupt company unless they believe the enterprise is worth more than what they are putting in. That commitment suggests backers see a going concern in Brightline's routes and stations, even if the original capital structure could not support them.
Who absorbs the loss
Much of Brightline's debt was raised in the municipal bond market, which makes the case a closely watched test for investors who bought infrastructure exposure through tax-exempt paper. Those holders typically expect stable, long-dated income, and a restructuring that converts debt into equity or extends maturities would reset their returns.
The details that will define recoveries, including the size of any debtor-in-possession financing and the final reduction in debt, are set to come into focus at the first-day hearing and in subsequent plan filings.
What to watch
The first-day hearing will show how much operating liquidity the court approves and whether any creditor group objects to the plan. Beyond that, the timeline to confirmation will be the key measure of whether the prearranged approach works. A case that moves from filing to exit in a matter of months would reinforce the appeal of the playbook for other sponsor-backed infrastructure assets under pressure from higher rates.