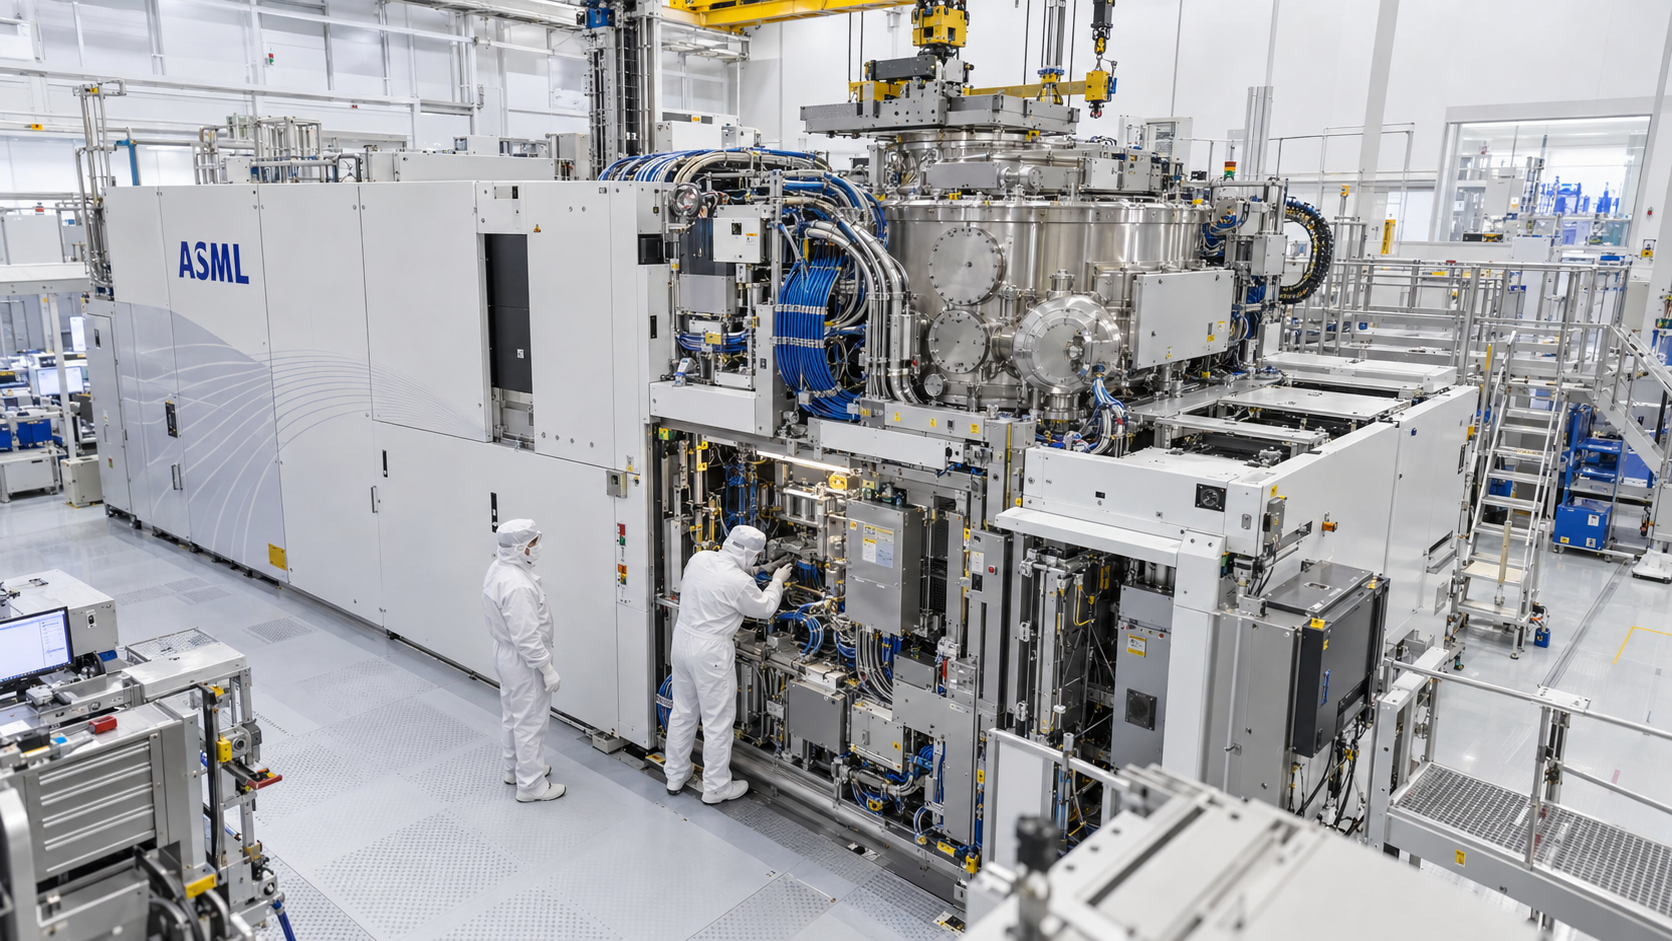
Third-quarter sales reached a record €11.7 billion, and profit, helped by a one-time gain on its Mistral AI stake, beat forecasts. The chip-equipment maker said demand will outrun its planned capacity for two years, one session after its U.S.-listed peers sold off.
ASML's quarter was strong. What it said about the next four years was stronger.
The Dutch maker of lithography machines reported third-quarter net sales of €11.66 billion on Wednesday, up 25% from the second quarter and 55% from a year earlier, toward the top of its own €11 billion to €12 billion guidance. Net income rose to €4.96 billion, or €12.95 a share, from €2.92 billion in the second quarter, including a gain of about €510 million from revaluing the first tranche of its investment in Mistral AI. Gross margin widened to 57.5% from 54.0%.
Against analysts' forecasts compiled by LSEG, profit beat the €4.1 billion consensus by about 21%, or about 10% excluding the Mistral gain. Sales were a fraction below the roughly €11.72 billion expected, a gap of about 0.5%.
The capacity problem
The headline numbers were overshadowed by a statement about supply. "With such strong visibility and an order book momentum that continues to increase quarter on quarter this year, we now expect that our supply as currently planned for both 2027 and 2028 will not fully meet the demand of our customers," Chief Executive Christophe Fouquet said.
That plan was already aggressive. With its second-quarter results, the company said it would raise capacity for its main low-NA extreme ultraviolet and DUV immersion tools by 30% in 2027 and was studying a further 30% increase for 2028. It is now "investigating ways to increase capacity for 2028 beyond the 30% increase we previously communicated."
Customers are looking further out still. They "continue to increase their short- and medium-term equipment demand forecasts with us, driven primarily by their views on the size and duration of AI-related investments," Fouquet said, and "some customers are expressing an interest in placing orders with us for 2029 and even 2030."
ASML stopped reporting quarterly bookings this year, so the strength of the order book is described rather than measured.
The guidance
ASML expects fourth-quarter sales of €14.2 billion to €15.2 billion with a gross margin around 57%. The bottom of that range is in line with the roughly €14.2 billion analysts expected, and the margin guidance is above the roughly 55.4% they had forecast. The midpoint, €14.7 billion, would be about 26% above the third quarter. For the full year the company expects €44 billion to €45 billion of sales and a gross margin near 56%.
Service and upgrade revenue, which ASML calls installed base management, came in above guidance at €3.29 billion, and the company sold 113 new lithography systems against 86 in the second quarter. It bought back about €4.1 billion of shares in the quarter and will pay an interim dividend of €1.88 on Nov. 4. Cash and short-term investments rose to €12.7 billion from €7.6 billion.
The day before
The results landed after a rough session for chip-tool makers. On Tuesday, Applied Materials fell 6.69%, KLA 3.22% and Lam Research 2.73%, and ASML's U.S.-listed shares dropped 1.86% to $1,717.76. The VanEck Semiconductor ETF fell for a sixth straight session.
Technology led European sectors higher in early trading on Wednesday, and by late morning in Amsterdam ASML shares were up about 1.9% at €1,538.20.
Market implications
One reading is that the supply constraint is the bull case in plain sight. A supplier of the most advanced lithography tools saying its planned supply will not fully meet demand for two years, with customers discussing orders for 2030, supports pricing power and margins well beyond the current quarter.
A second reading is that the market has heard the AI demand story and wants proof. Sales were roughly in line, a one-time gain flattered the profit beat, the order book is described in words rather than figures, and chip-equipment shares were sold hard the day before the report, a sign that investors are questioning how long the spending cycle runs rather than how strong it is now.
What to watch
ASML's investor call at 9 a.m. Eastern may bring order or capacity figures. Taiwan Semiconductor Manufacturing's results on Thursday, and its spending plans for 2027, are the next test of whether customers are acting on the demand ASML describes.