Ares funds are paying an enterprise value of roughly $2.9 billion for Infinity Transportation. The seller is KKR, through Global Atlantic, the insurer it now wholly owns, which has invested in the railcar lessor since 2016. Three days earlier, Carlyle announced a deal to take $7.7 billion of personal loans off Truist's balance sheet.
Divide the price by the fleet and the Infinity deal comes to roughly $58,000 of enterprise value per railcar, by this publication's arithmetic, before any value is assigned to the intermodal equipment that Infinity also leases. That is the closest thing to a valuation marker the two sides have offered, and it says something about who is now setting prices for long-lived hard assets.
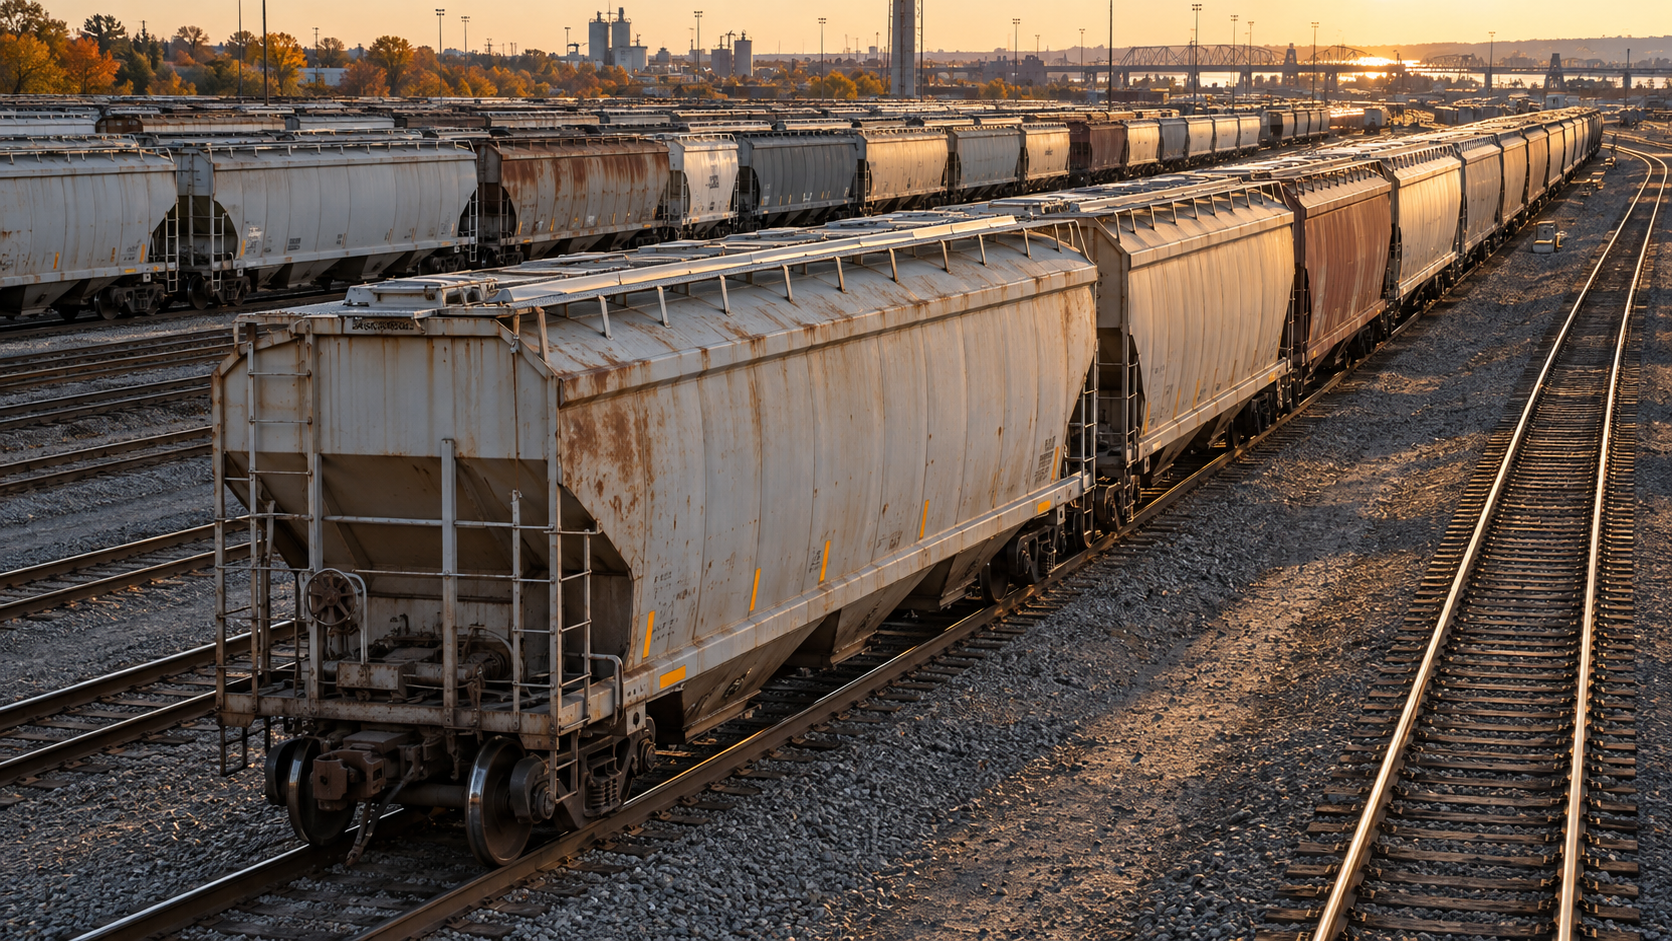
Ares Management will acquire Infinity Transportation from KKR at an enterprise value of about $2.9 billion under a definitive agreement announced on Monday. The buyers are funds managed by Ares Infrastructure Equity and Ares Insurance Solutions. Infinity owns and manages about 50,000 railcars leased to more than 350 customers in the U.S., Canada and Mexico. The parties expect to close in the first quarter of 2027, once regulators sign off.
Insurance capital on both sides
Global Atlantic, the insurer KKR began acquiring in 2021 and has wholly owned since 2024, has invested in Infinity since 2016. Infinity became a standalone platform in 2021 with KKR's support, and KKR says its book value has grown 150% since then.
So the business is leaving an insurer's portfolio and joining a buyer group that includes insurance-focused funds. That is the logic of asset-based finance in practice: a railcar on a multiyear lease throws off steady rent for decades, which suits capital that owes annuity holders steady payments for decades. Daniel Pietrzak of KKR framed the sale around the value of long-term capital in the asset class, and Ares executives cited reshoring and supply-chain investment as the case for owning North American rail equipment.
One week, two balance sheets
The deal did not arrive alone. On Oct. 16, Carlyle announced that it had agreed to buy about $7.7 billion of unsecured personal loans from Truist's LightStream unit, saying banks are increasingly turning to private capital. Taken together, the two transactions put roughly $10.6 billion of assets in motion toward private capital in a single week, by this publication's arithmetic. One came from a bank's consumer book, the other from a sponsor's insurer.
For scale, Infinity's enterprise value equals well under 1% of the more than $671 billion Ares managed at the end of June.
The question the price leaves open
When buyer and seller both value assets largely by appraisal, a sale may prove less about market value than an auction among strategic buyers would. KKR's 150% book-value gain is the seller's own measure. The split between Ares' infrastructure fund and its insurance funds, the amount of debt in the structure and KKR's realized gain were not part of Monday's announcement.
Market implications
One reading is that this is efficient matching. Long-dated, contracted lease income belongs with long-dated liabilities, and an insurance-backed buyer can pay a full price because its funding is patient.
A second reading is that the trade concentrates illiquid, appraisal-valued assets in insurance-linked portfolios, moving them between similar pools of capital without a market-clearing test of their worth.
The observable that separates the two is what KKR books. A realized gain at or above the carrying value in Global Atlantic's results would suggest the price cleared the appraisal; a sale at or below it would suggest the buyer set the terms.
What to watch
KKR's and Ares' third-quarter results and any detail on financing and the fund-versus-insurance split; regulatory filings tied to the close; further bank portfolio sales to private credit managers; and insurance regulators' scrutiny of private asset concentrations.